
State of the Canadian Pre-Roll Market 2026
Posted by Brian Beckley on Sep 29th 2026
With a growth rate that has outperformed the industry as a whole in each of the past five years, the pre-roll category has long sold more units than any other in Canada.
But in 2025, pre-rolls not only expanded their lead in unit sales, but became the top category by revenue, securing its position as the key driver of the entire Canadian cannabis marketplace.
Even as industry revenue growth plateaued at 2.7% in 2025 and unit sales saw a modest 3.6% increase, pre-rolls grew more than 6% in both metrics, helping set the pace.
This year, infused pre-rolls closed the gap on hybrids, virtually tying for the leading revenue segment and should take over the top spot in 2026. Additionally, the indica pre-roll became the latest industry trend, delivering the biggest growth of any segment.
Drawing on sales performance data, product-level trends, SKU analysis and industry expertise, this report examines the data behind those shifts and looks forward to the trends that will define the future of pre-rolls, including:
- the continuing shift toward infused and premium products;
- the dominance of multi-pack formats; and
- emerging opportunities for growth in an increasingly competitive marketplace.
Looking ahead, the report projects continued but decelerating growth: national pre-roll revenue is forecast to reach roughly $1.5 billion in 2026, $1.85 billion by 2030, and $2.1 billion by 2035, as the market advances toward maturity.
About This Report
This analysis is drawn from comprehensive point-of-sale data, new product launch data and SKU-level performance metrics from four provinces – Ontario, Alberta, British Columbia and Saskatchewan – collected in 2025 by cannabis analytics firm Headset.
All of the data is presented in Canadian dollars.
Canadian Pre-Rolls by the Numbers
First let’s dive into the available Headset data to get a full picture of the pre-roll category and how it fits into the larger Canadian cannabis landscape.
2025 Pre-Roll Revenue and Market Share
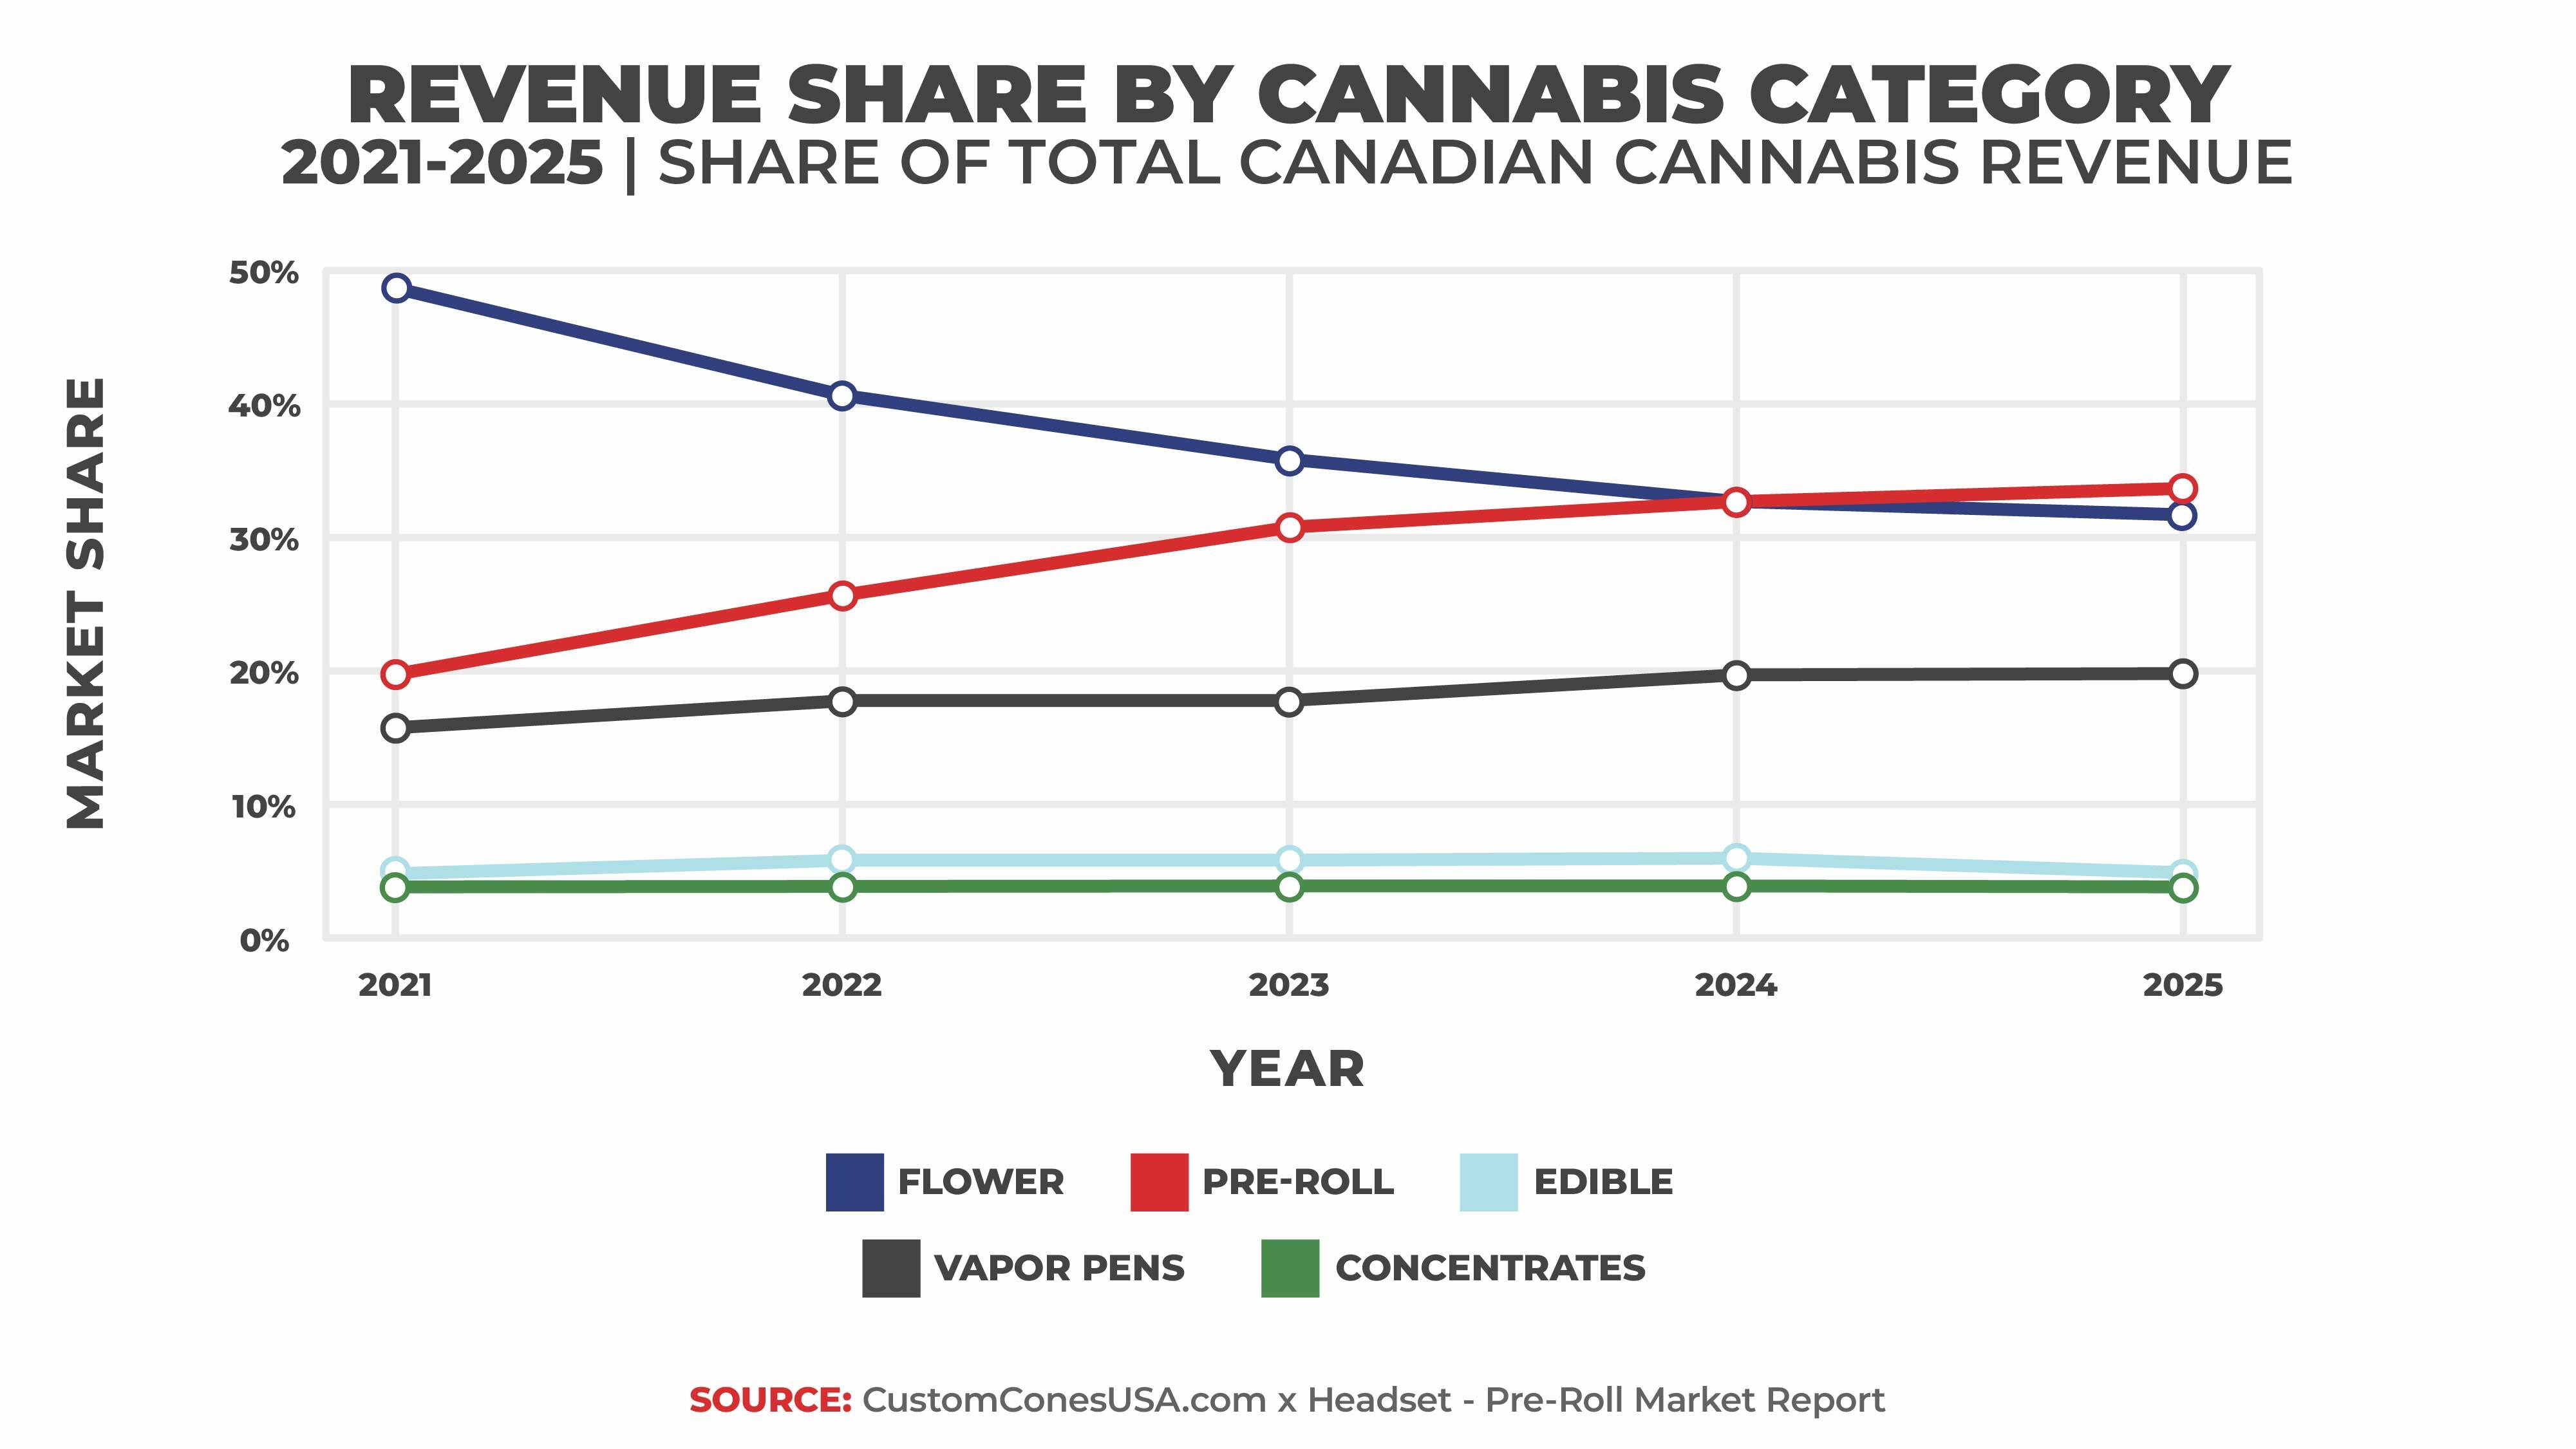
In 2025, pre-rolls became the dominant product form in Canada, passing flower in revenue with more than $1.4 billion in sales, reaching a market share of 34%. That’s up 6.3% over 2024’s total revenue number of $1.35 billion and an increase in market share by almost a full percentage point.
It marks the fifth consecutive year of growth in both revenue and market share for pre-rolls and a near tripling of the category’s revenue from just five years ago ($581 million in 2021).
And while that growth has slowed over previous years as the Canadian market has matured and begun to plateau, the pre-roll category at 6.3% was tied for the highest growth percentage of any major category in 2025 (with vapor pens). In fact, pre-rolls have consistently outperformed the Canadian cannabis industry as whole in terms of growth percentage.
Pre-rolls have also seen their revenue share grow every year since 2021, growing from just 20% in 2021 to surpass flower in 2025 with an industry-leading 34%. Most of the category’s gains have come at the expense of flower.
2025 Pre-Roll Units Sold
When we turn from revenue to units sold, the pre-roll category’s dominance is even more pronounced, with Canadian consumers buying nearly twice as many pre-rolls as any other product category.
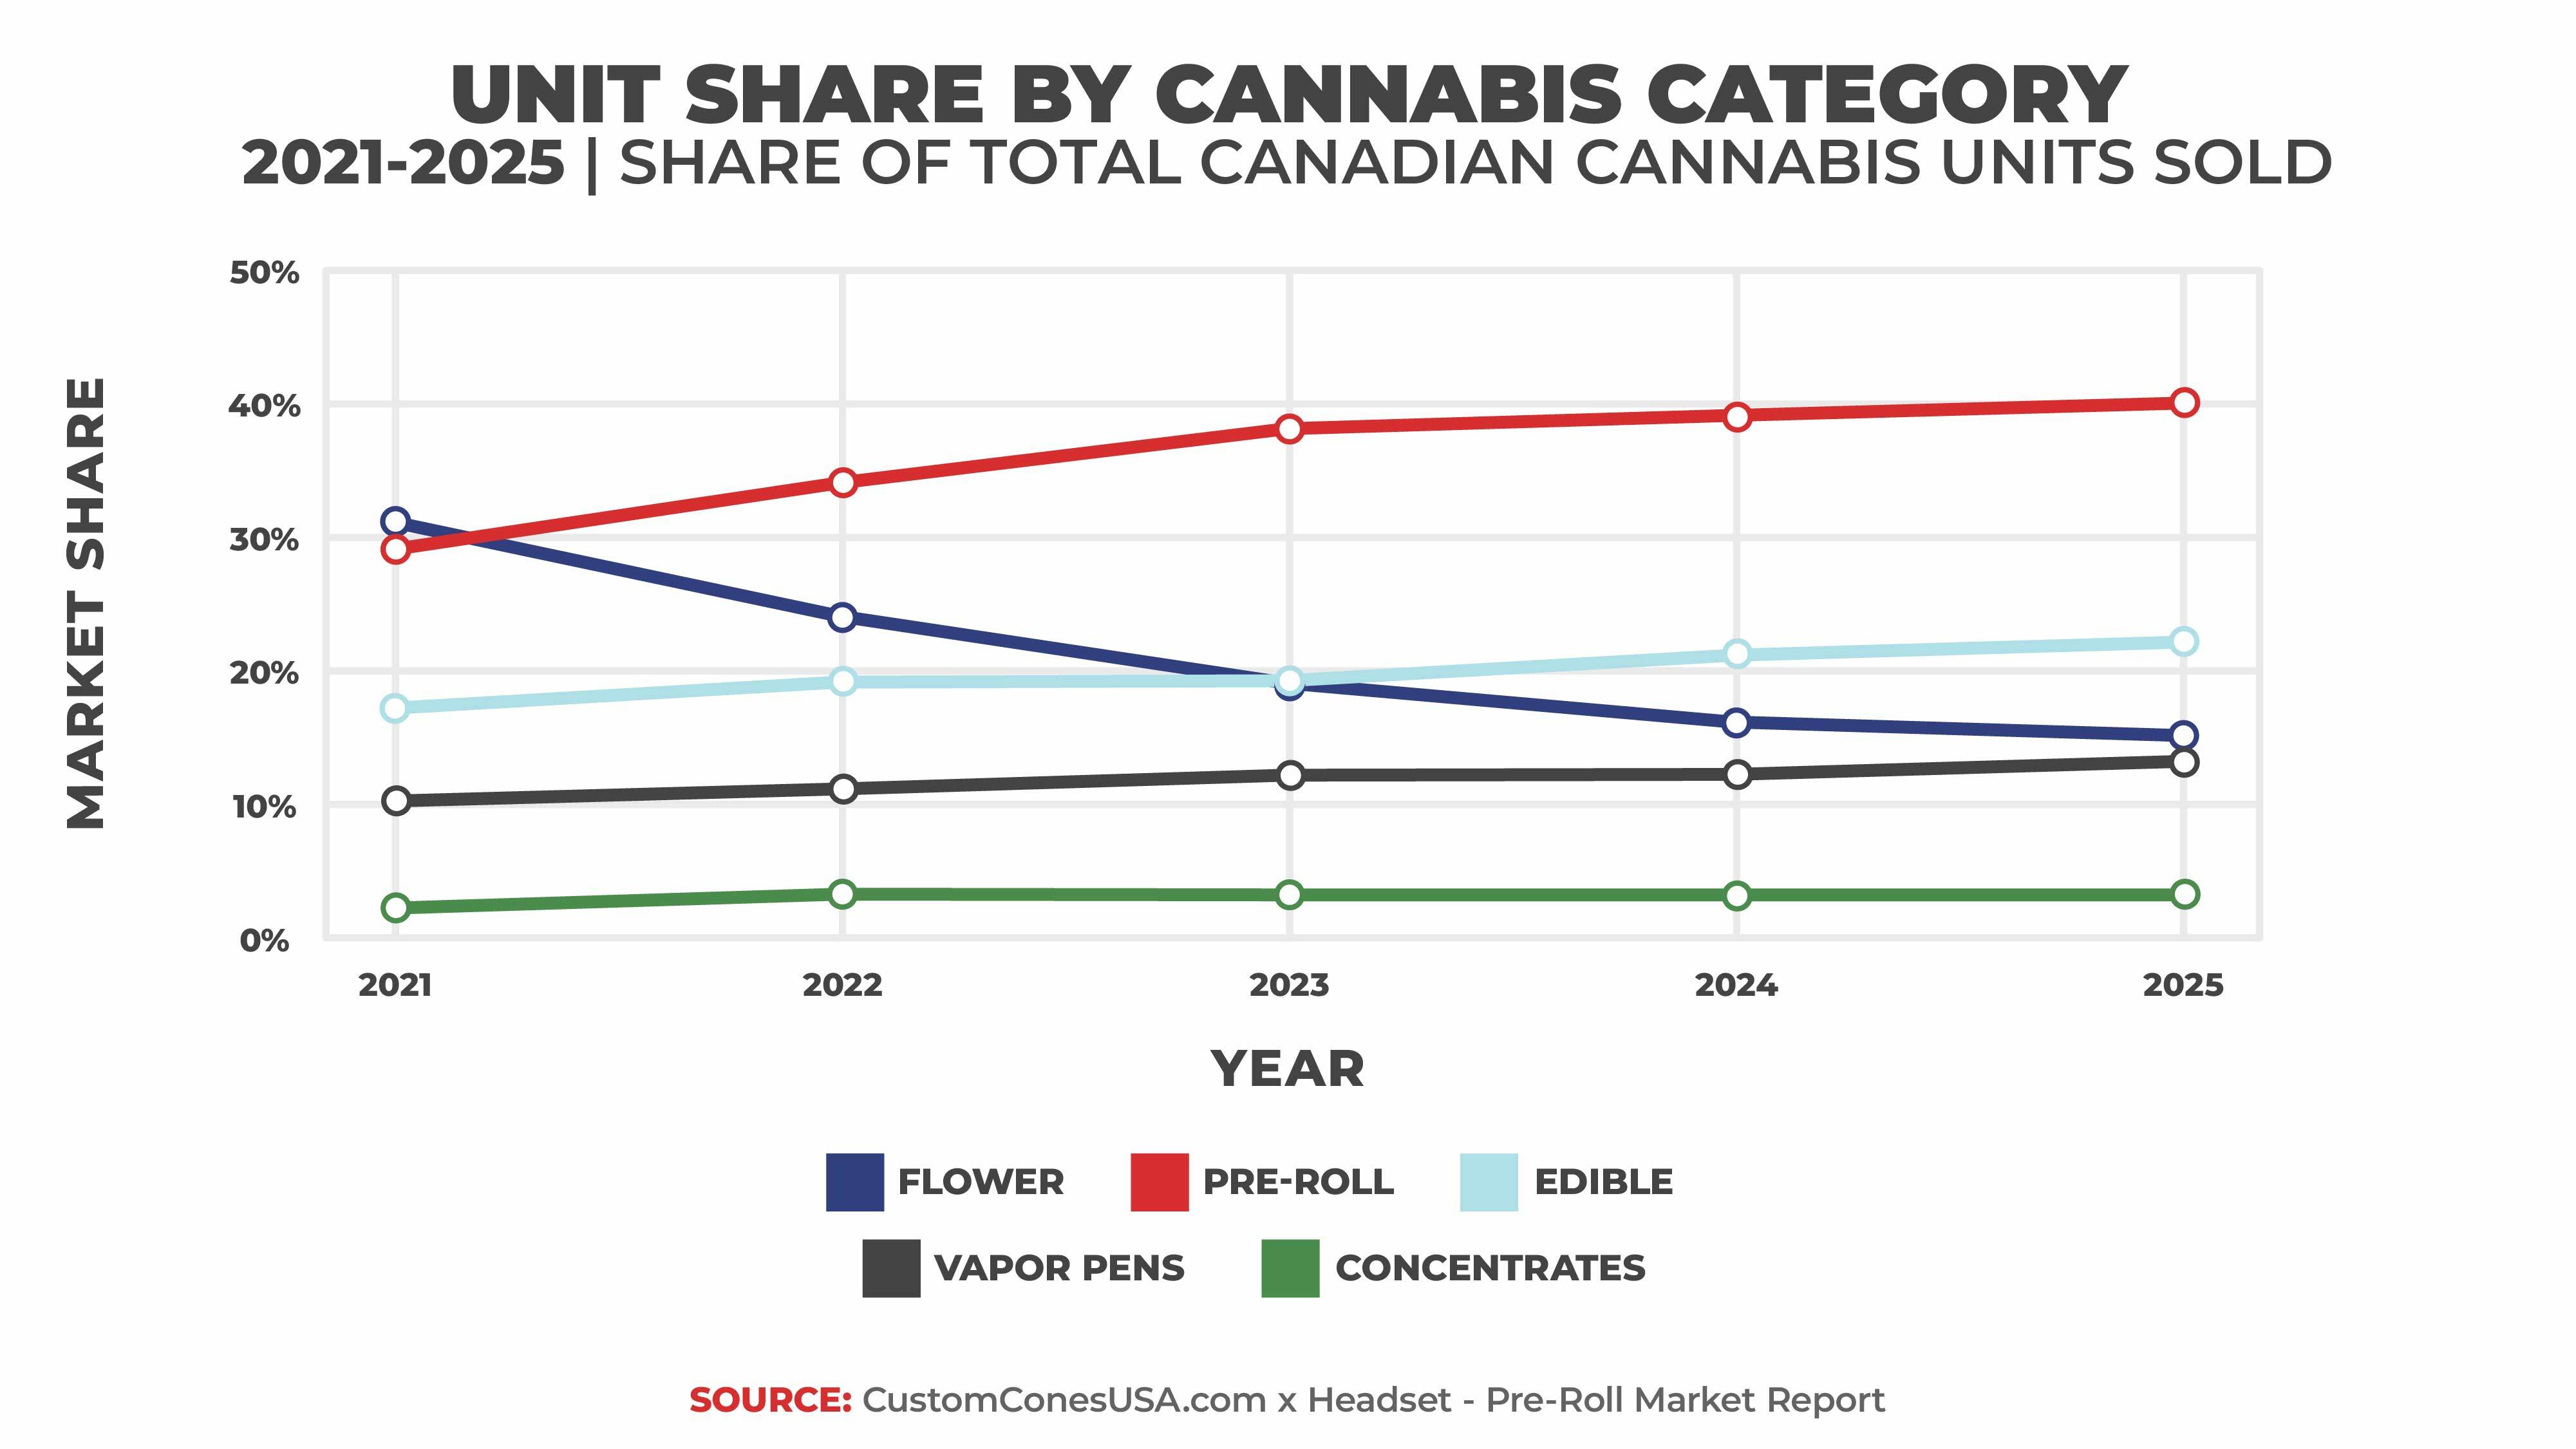
Canadian retailers moved about 77.2 million pre-roll units in 2025, up from 72.7 million in 2024, or about 39.7% of all units sold. That’s a year-over-year growth of 6.1%, third-best in the units sold metric behind edibles (6.8%) and vapor pens (6.2%).
However, despite leading in growth, edibles still ranked a distant second with 41.9 million units sold, for a market share of 21.5%. That’s up from 39.2 million in 2024.
Flower, meanwhile, saw a decline in unit sales in 2025, dropping from 30.7 million in 2024 to 29.3 million in 2025.
A History of Pre-Roll Growth
2025 marked the fifth consecutive year that pre-roll revenue and units sold grew. And looking at the larger picture, no category has grown more in the past five years than pre-rolls, no matter which metric you use, growing from a mid-tier category in 2021 to the clear market leader by 2025.
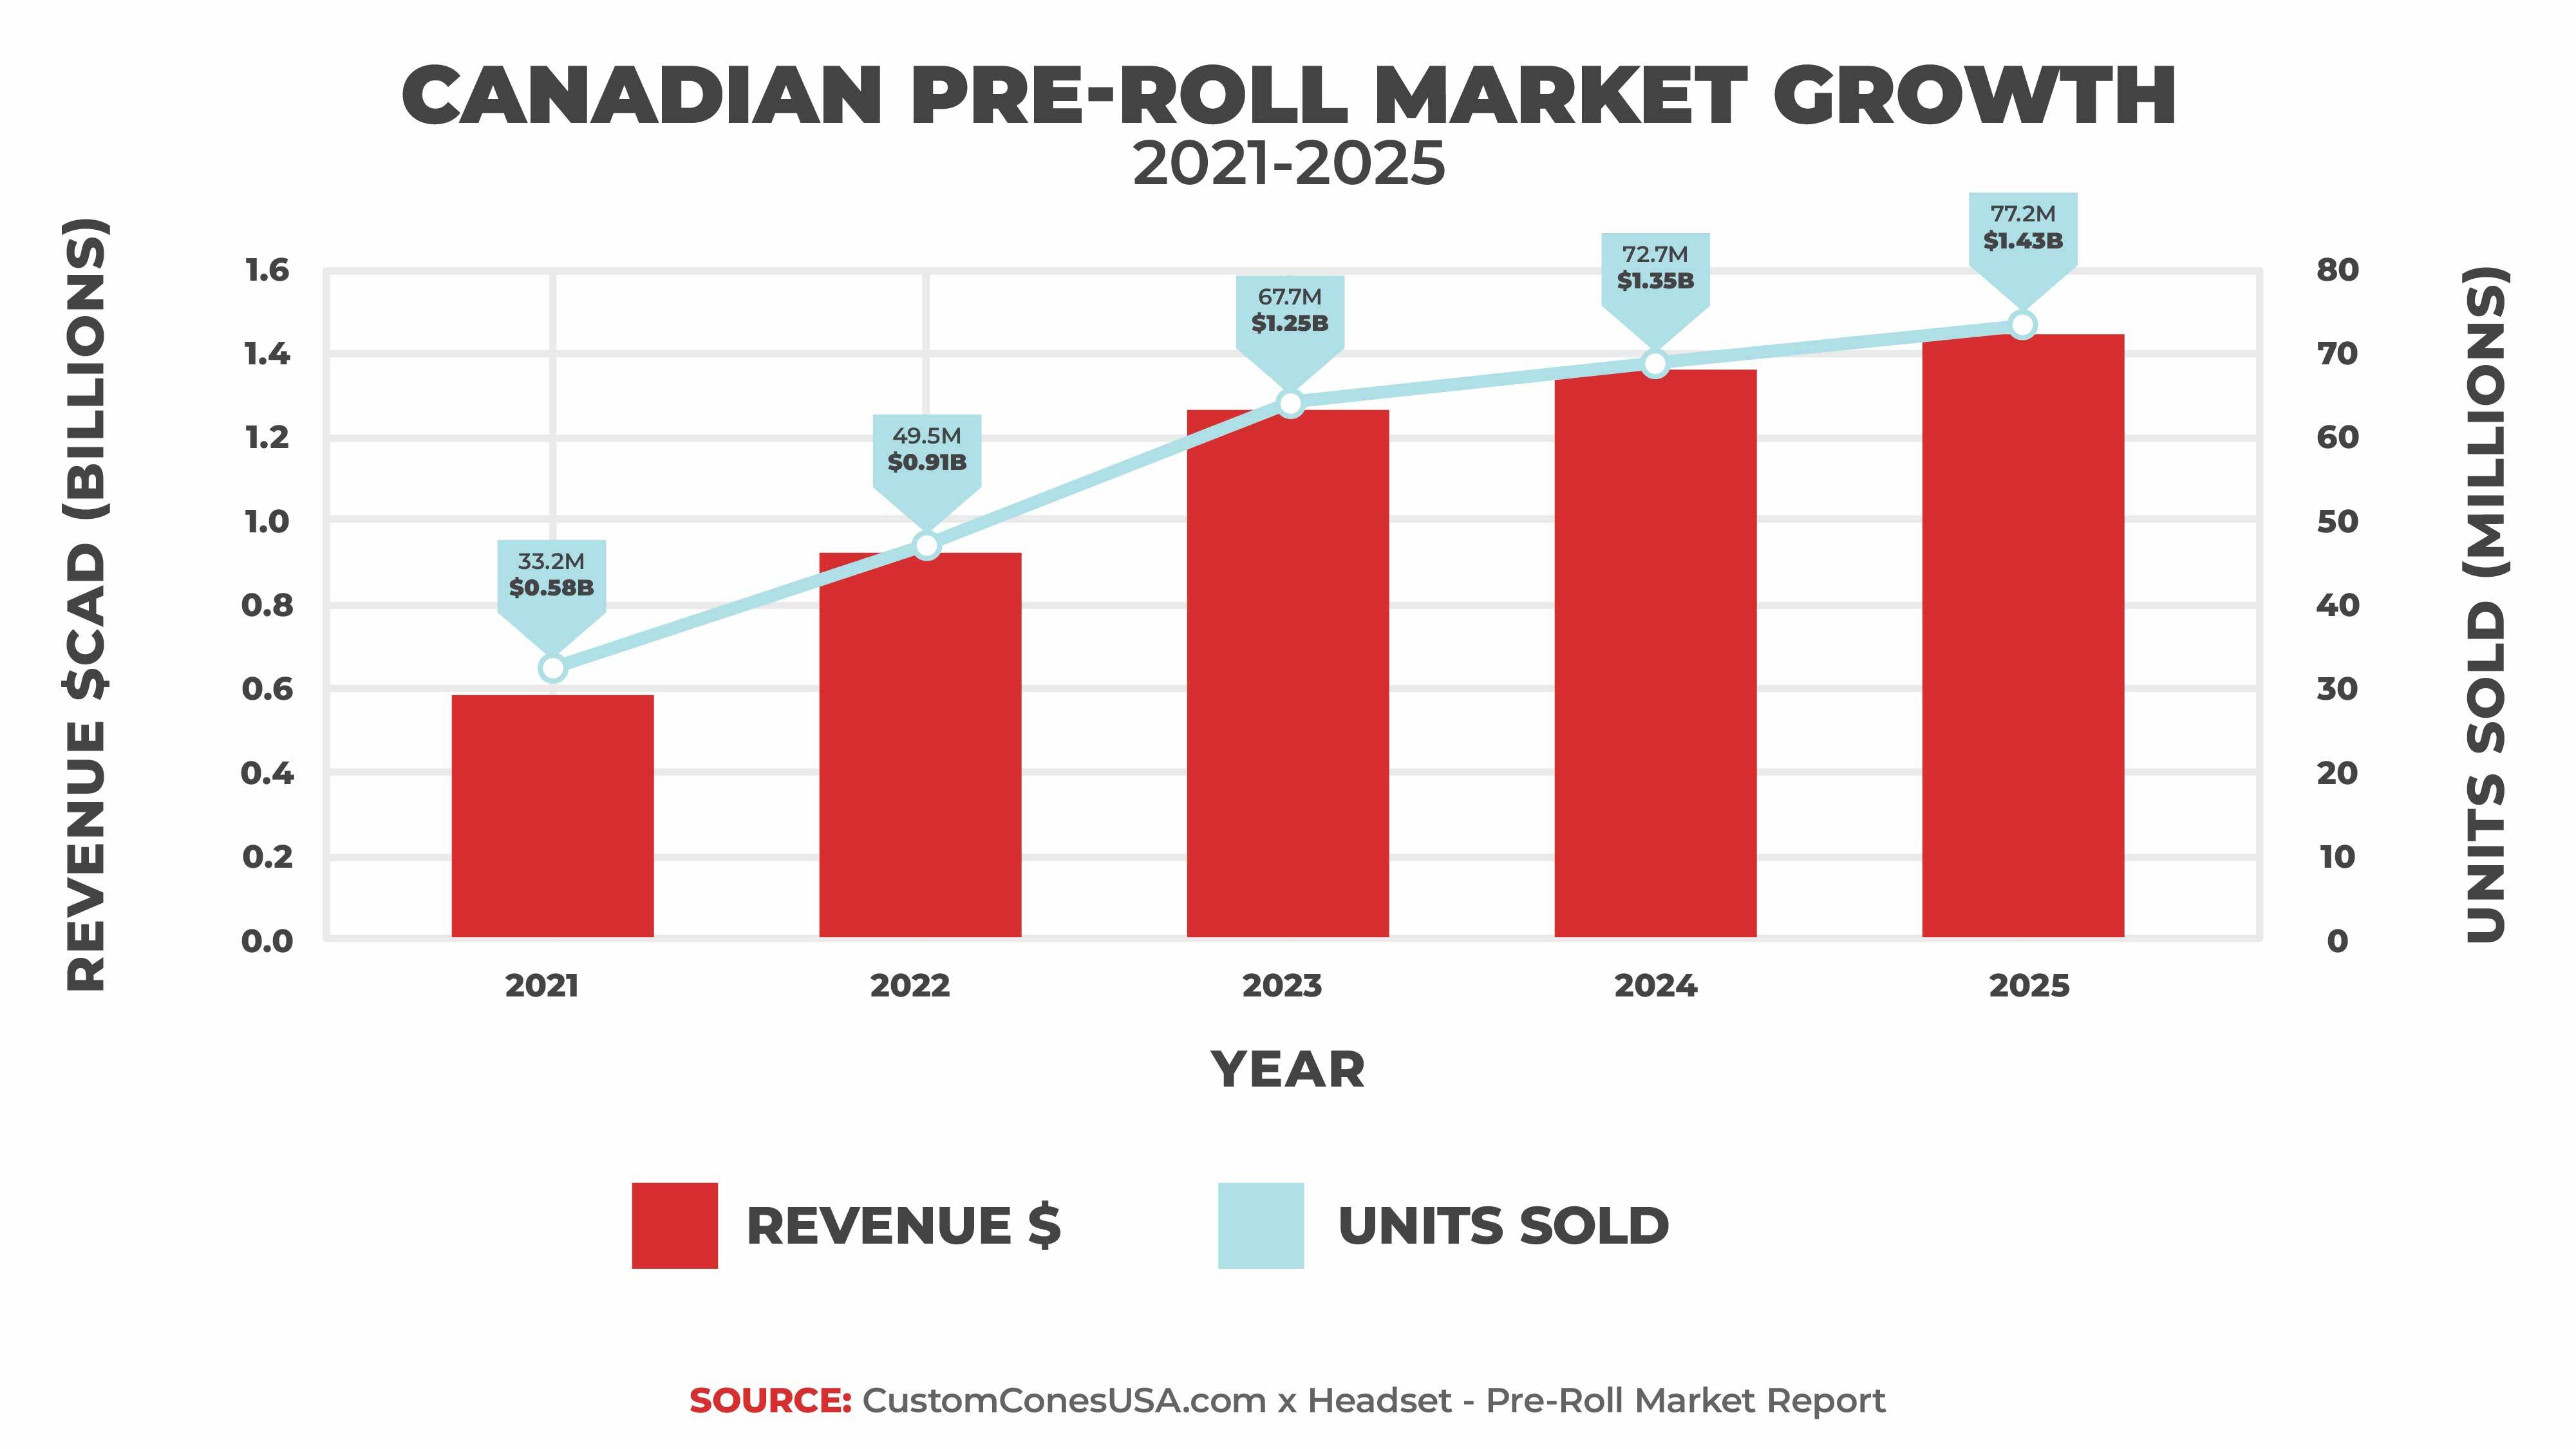
In terms of revenue, pre-rolls have jumped from $581 million in 2021 to $1.43 billion in 2025, growth of 146.6%.
Switching the focus to units sold, pre-rolls go from 33.2 million in 2021 to 77.2 million in 2025, growth of 132.3%.
And generally speaking, it's not close. Vapor Pens are second in revenue growth over the same period at 80.8%, while edibles take the second spot in units sold with a growth rate of 114.4%.
2025 Canadian Pre-Roll Segments
While pre-rolls as a whole continue to grow in every metric, it is not a monolithic category, but one that is dynamic and innovative. When we dive deeper into the segment numbers, there are a few noteworthy trends worth mentioning.
Hybrid pre-rolls rule, but Infused pre-rolls gaining
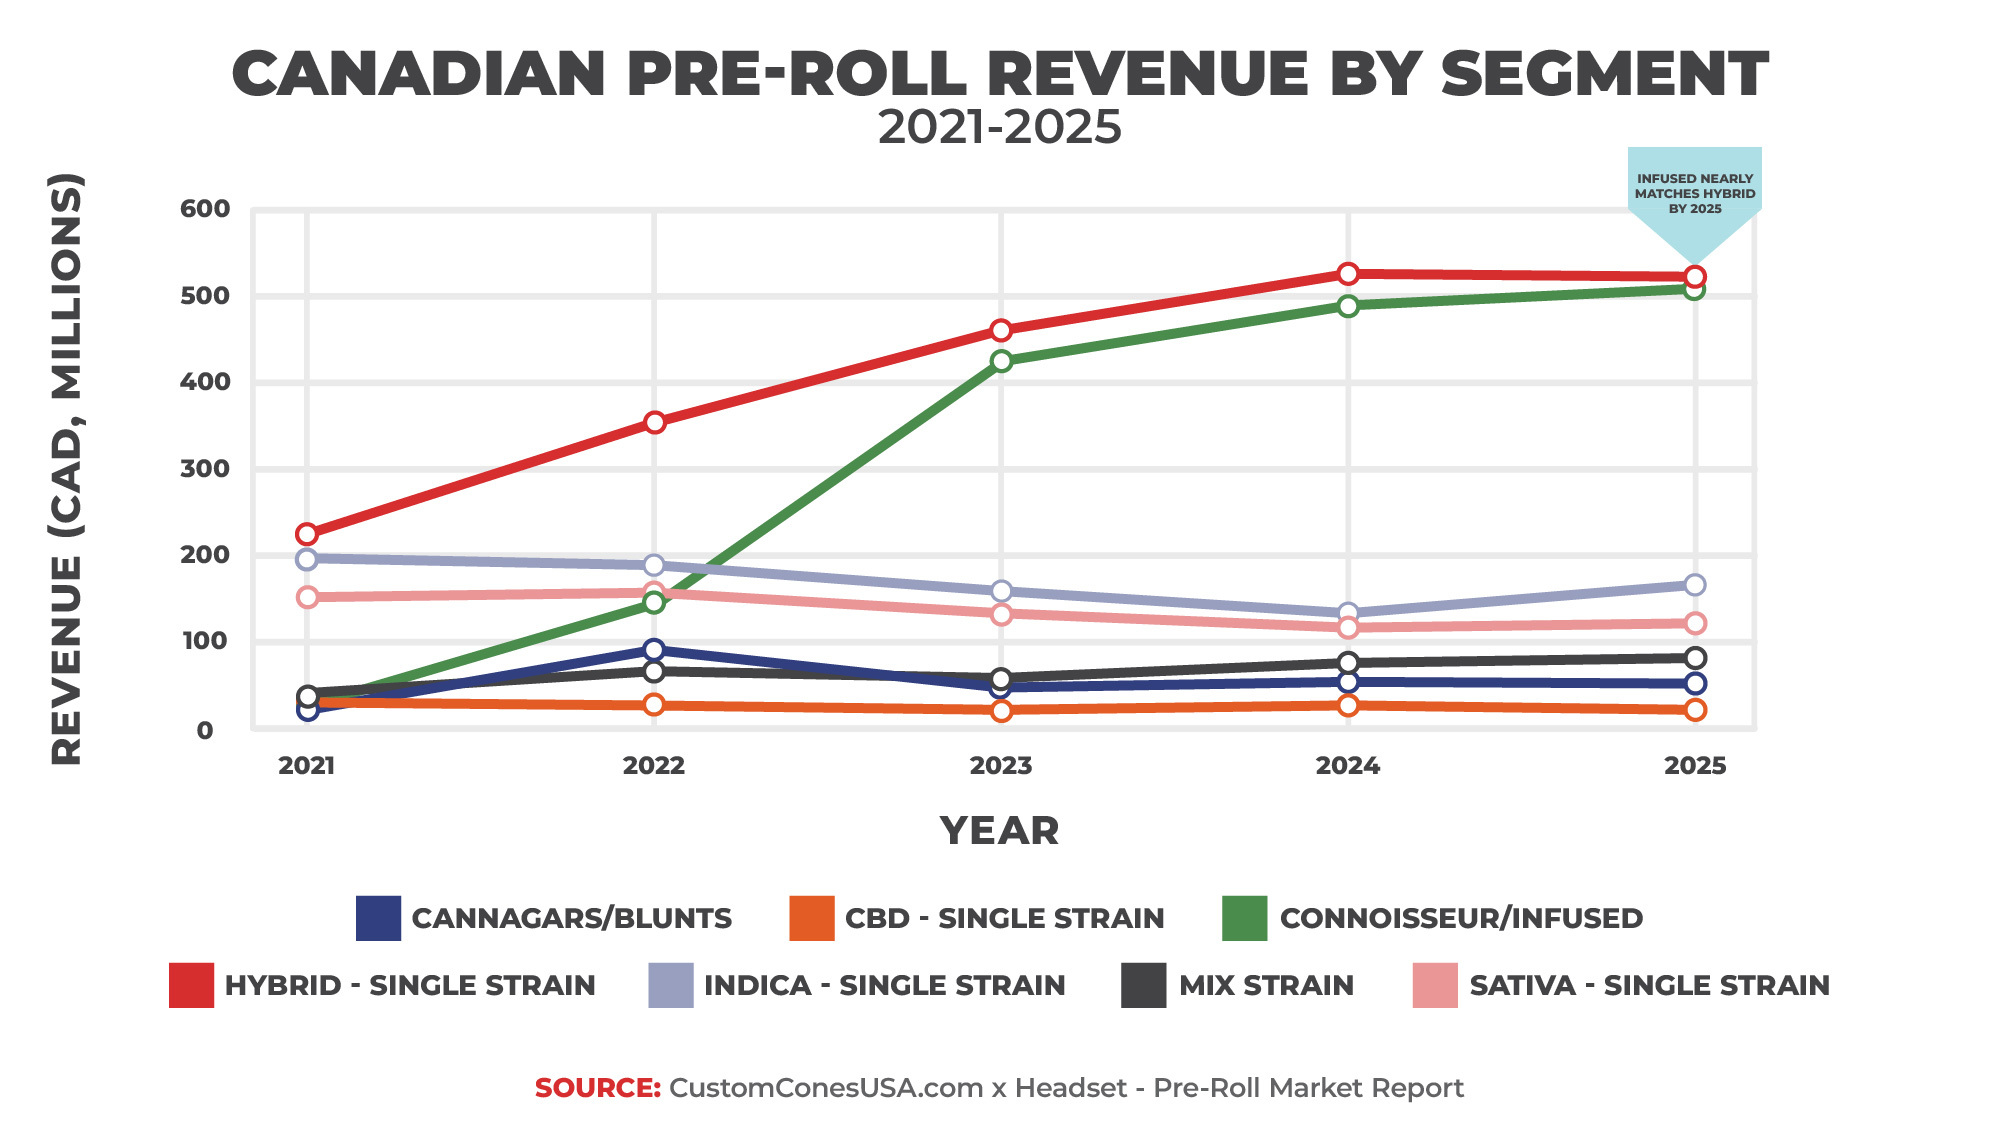
The top segment in the Canadian market continues to be the Hybrid – Single Strain, however this may be the last year it retains the title as infused pre-roll products, with their increased potency and higher price point, continue to grow in popularity.
In 2025, Canadians bought more than 31.2 million hybrid pre-roll units, bringing in $525.5 million dollars in revenue on an average price point of $6.56 per unit. That’s up from $507 million in 2024 on sales of 29.8 million units, year-over-year growth of 3.7% and 4.7%, respectively.
The numbers for infused pre-rolls, which combine flower and a concentrate in a single pre-rolled cone, have continued to grow through the years and in 2025, the segment’s revenue was nearly equal to that of hybrids, coming in at $523.6 million dollars, up from $507 million in 2024. That’s a growth rate of 7.3%. Unit sales for infused pre-rolls still lagged behind, however, with 20.6 million (up 2.4% from 20.2 million in 2024), though the significantly higher average price point of $25.39 per unit boosts the revenue numbers.
Together, the hybrid and infused categories account for 73.2% of all pre-roll revenue and 67.2% of all unit sales.
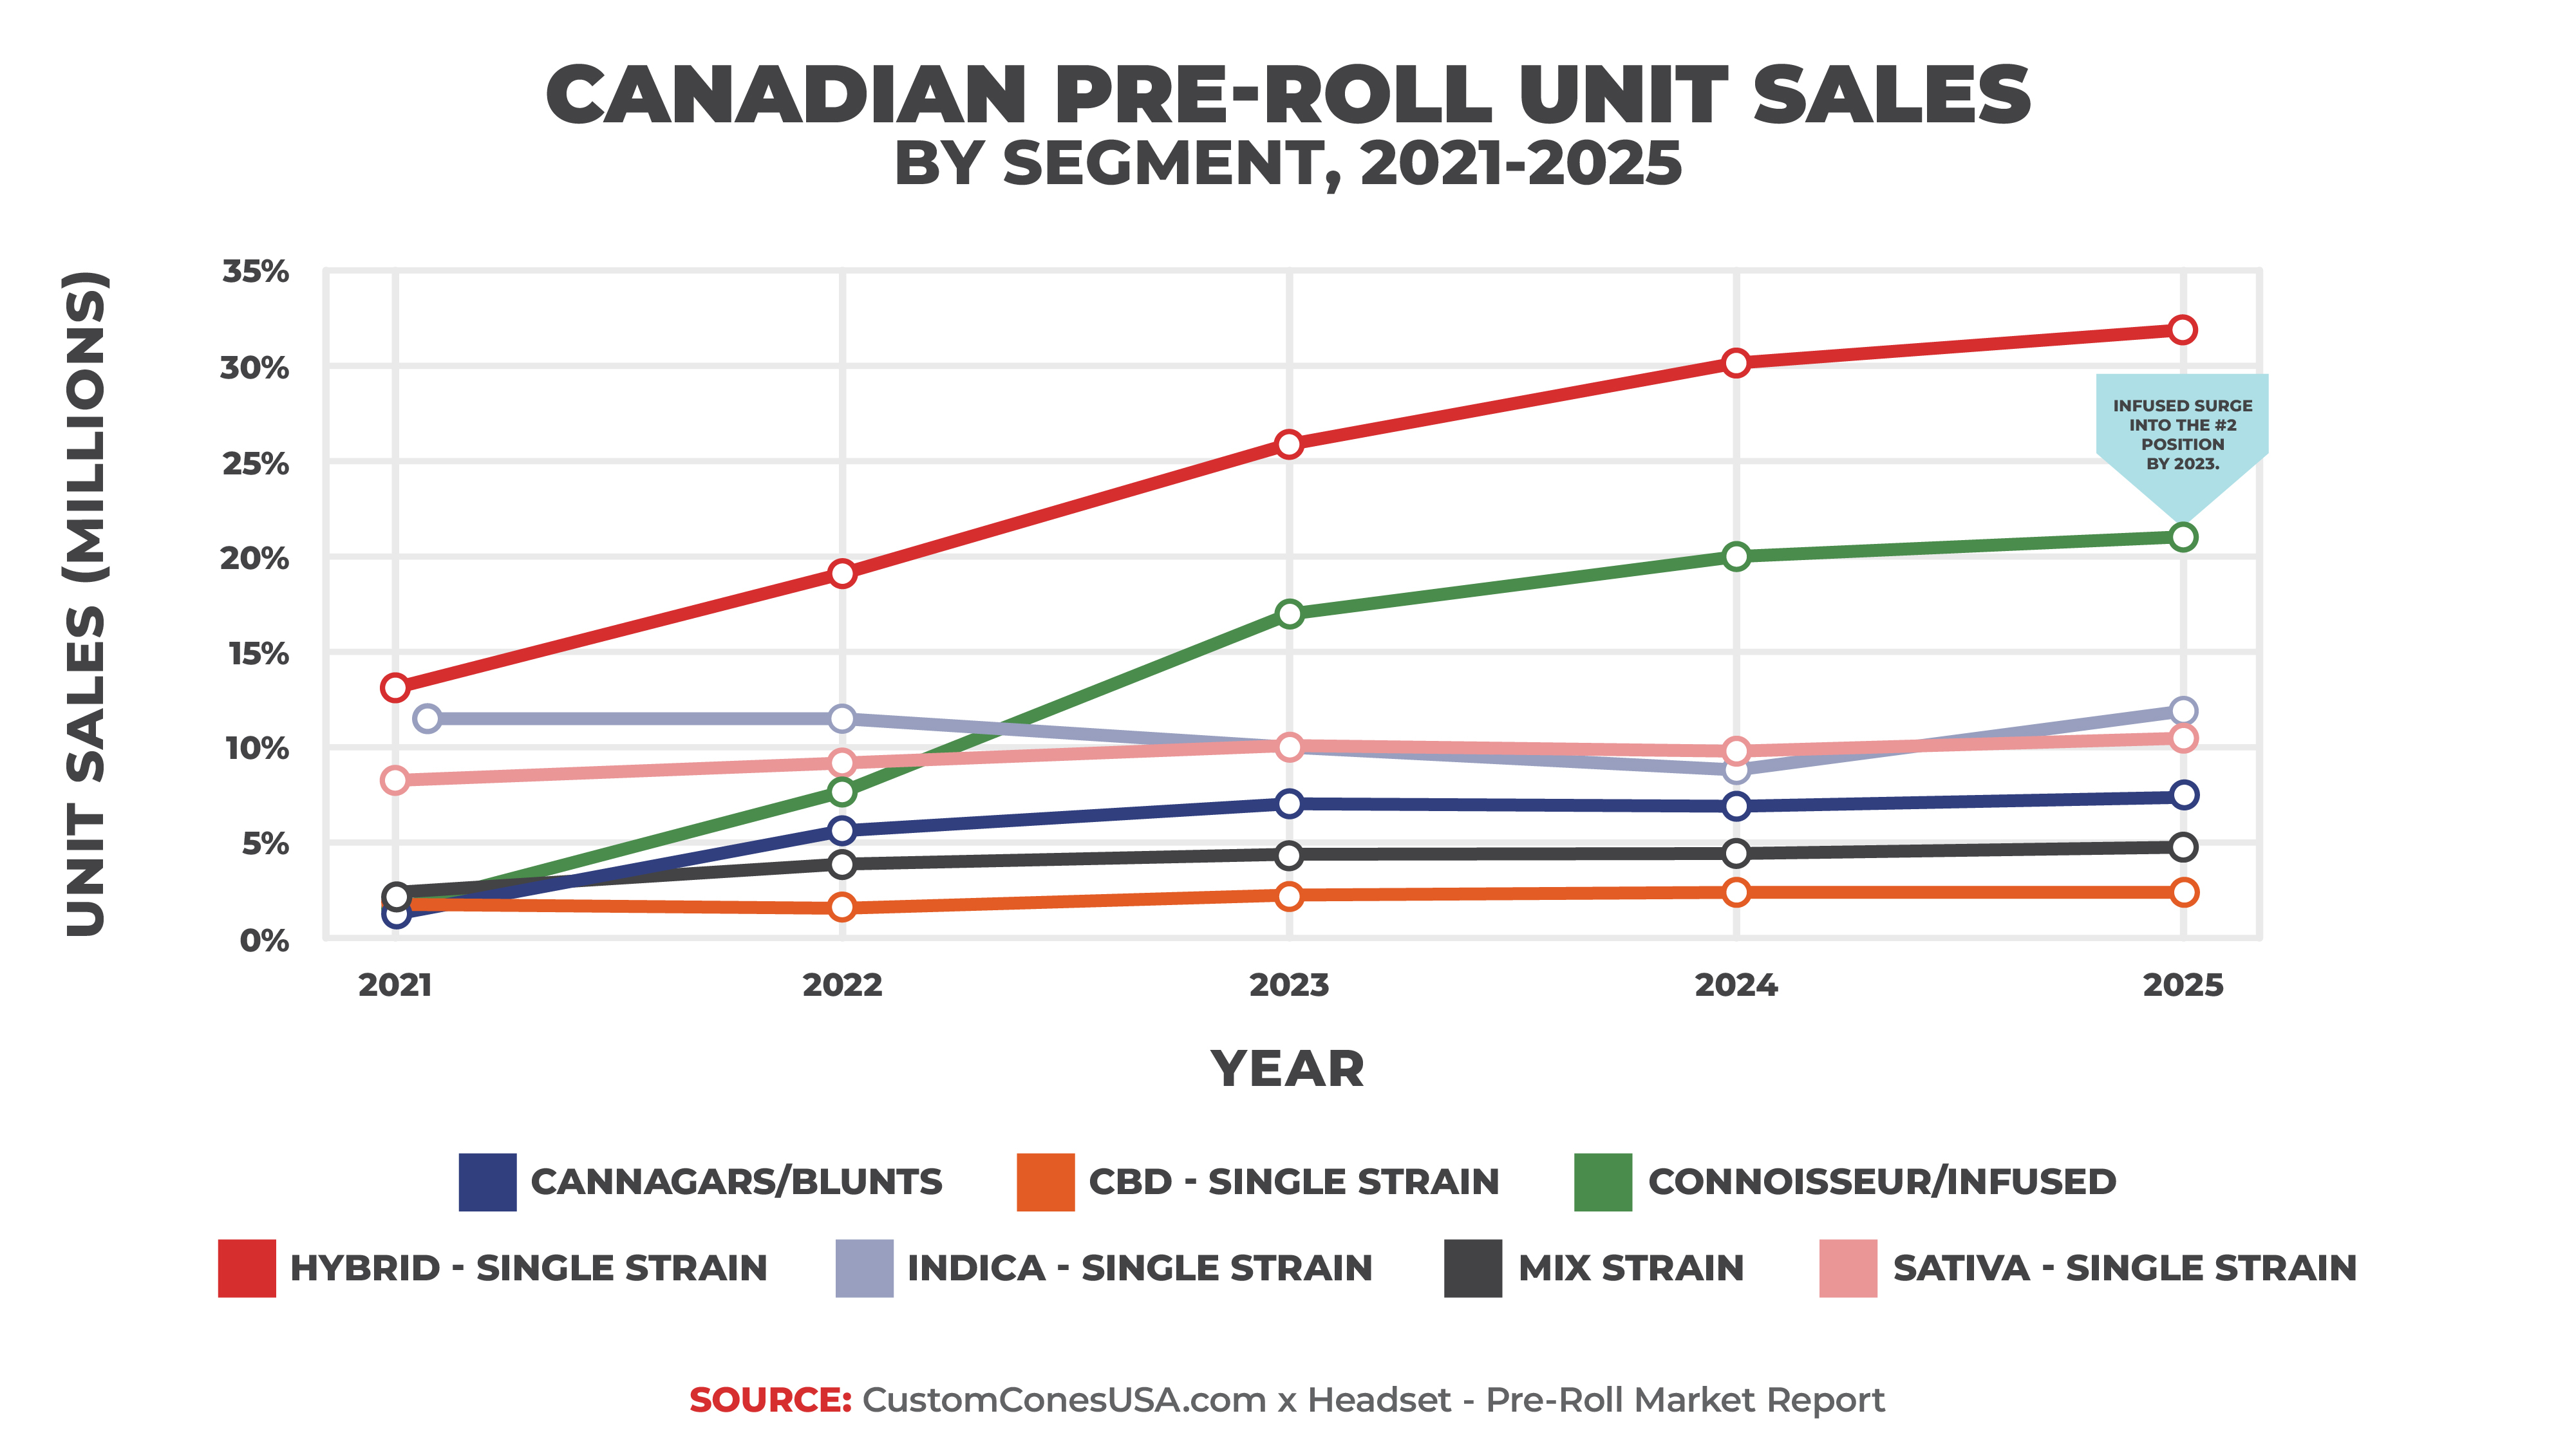
The biggest growth segment in 2025, however, was the indica pre-roll, which saw year-over-year growth of more than 20% in both revenue and units sold. In 2025, indica pre-rolls were the third category in both revenue and unit sales, raking in $172 million on unit sales of about 11.6 million, up from $142.6 million and 9.4 million in 2024. That’s year-over-year growth of a whooping 21.2% and 22.8%, respectively. Indica pre-rolls have an average price of $14.93 per unit.
Sativa pre-rolls follow close on the indica segment’s heels, generating revenues of $142.7 million on sales of 10.4 million units with an average price point of $13.71.
Rounding out the category are mixed strain pre-rolls at $40 million in revenue on sales of 1.4 million units ($29.61 average price per unit), blunts at $21.7 million on sales of 1.7 million units ($12.44 average price) and CBD pre-rolls at $6.6 million on sales of about 299,000 units ($21.97 average price).
Canadian Pre-roll Pricing in 2025
One reason for consistent growth in the pre-roll category is the relatively low price point of the products, which encourages experimentation and allows consumers to try new products and new strains without breaking the bank. However, prices vary depending on the type of pre-roll, size of pre-roll and province in which it is sold.
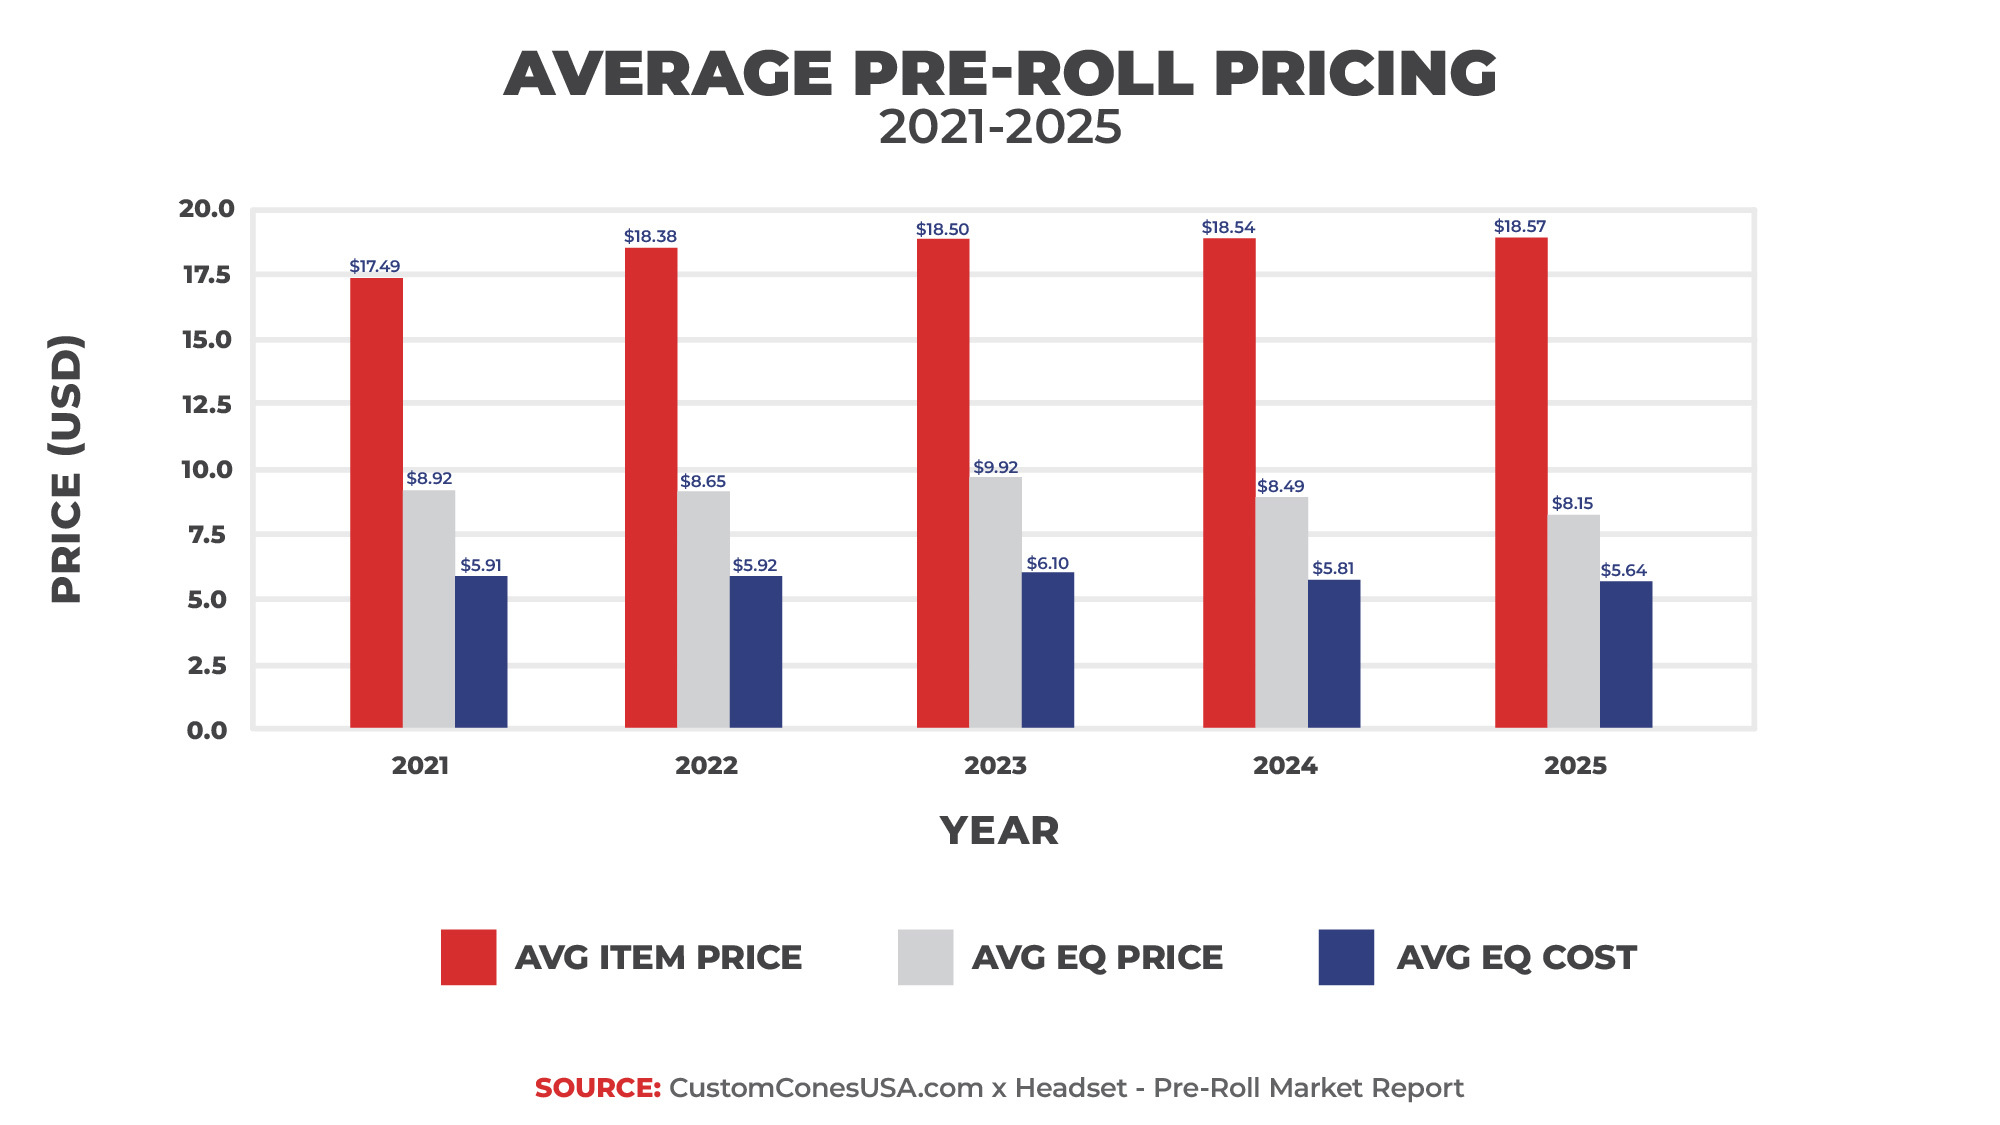
Overall, the average price of a pre-roll product has remained remarkably consistent for the past five years. In 2025, that average price was $18.57, up 3 cents from the 2024 average of $18.54, which was up just 4 cents from 2023.
Again, though, the numbers vary greatly between the segments. Mixed strain pre-rolls, which are usually sold in larger multi-packs, have the highest average price point at $29.61, followed by infused pre-rolls at $25.39 and CBD pre-rolls at $21.97.
The single-strain pre-rolls all hover around a similar average product price with hybrids at $16.83, indicas at $14.93 and sativas at $13.71.
However, because of the rise in multi-packs, which can vary greatly from segment to segment, average price point does not tell the full story.
When price is equalized for a 1-gram product, the list nearly flips with mixed strain pre-rolls coming in at $5.69 per gram, the lowest of any segment. Infused pre-rolls, on the other hand, are the most expensive at $15.19 per gram, which makes sense since they include both flower and concentrate and take additional labor to produce.
Indica pre-rolls are the second lowest at $5.98 per gram, followed by sativa pre-rolls at $6.38 and hybrids at $6.56. Rounding out the segments are CBD pre-rolls at $7.78 per gram and blunts at $10.19.
Overall, in 2025 the average equalized price of a pre-roll in Canada was $8.15 per gram, with the average cost to retailers being $5.64.
Pre-Roll Performance by Province
There are also variances within each of the four provinces tracked by Headset. Let’s dive a little deeper into the individual markets to see which pre-rolls are most popular where.
Ontario’s Pre-Roll Market
Unsurprisingly, Ontario’s pre-roll market is the largest in the country, topping the charts in both revenue and units sold, though interestingly, the pre-roll category ranks second in Ontario with a 32.7% market share.
Ontario consumers bought 40.3 million pre-roll units, generating $724.3 million in revenue. That’s an increase of 7.5% over 2024’s revenue and a 9.4% year-over-year increase in unit sales.
The average price of a pre-roll product in Ontario is $17.97, with the average equalized price at $7.90 per gram.
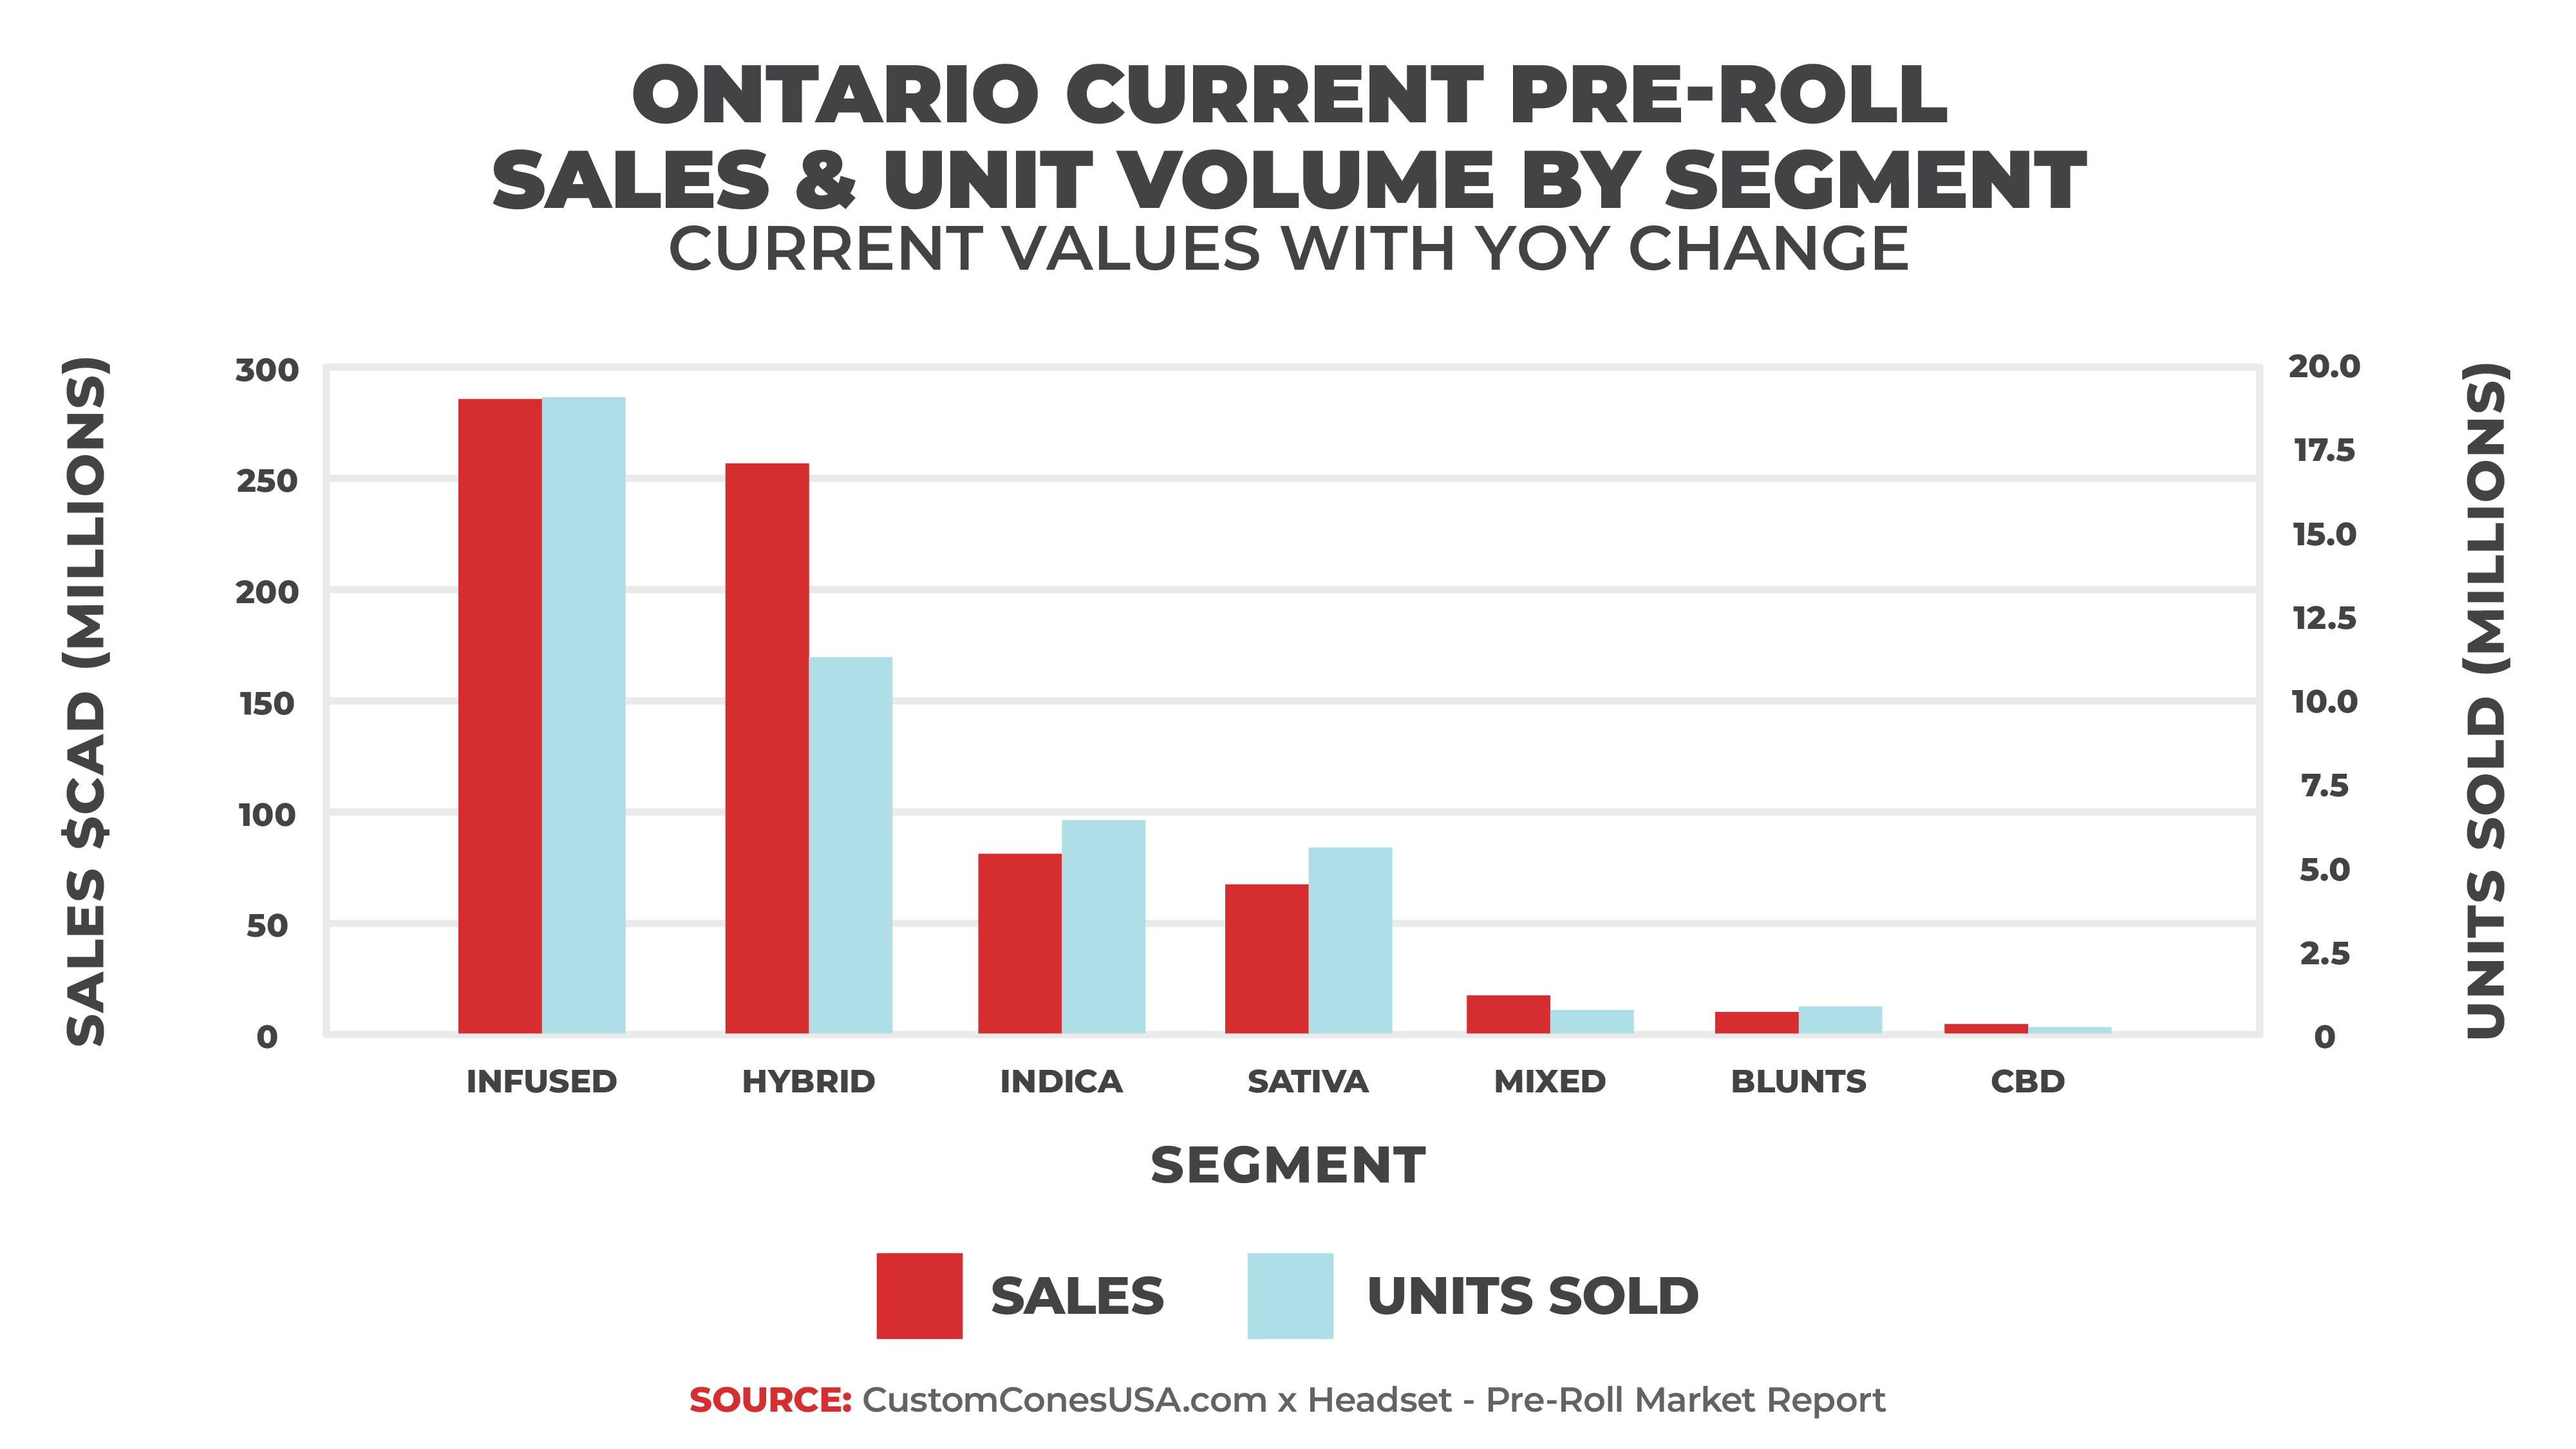
Diving deeper, Ontario consumers prefer hybrid pre-rolls, buying 17.5 million units and generating $287.3 million dollars, taking the top spot in both metrics. That’s up 5.5% and 8.8%, respectively, over 2024.
Infused pre-rolls follow at $257.6 million on sales of 10.3 million units, up 9.3% and 5.5% respectively.
Just as it is nationally, the biggest growth segment in Ontario is the indica pre-roll, which jumped 21.4% in revenue and 24.9% in unit sales to finish 2025 at $81.6 million and 5.9 million units, respectively.
The top pre-roll brand by in Ontario by revenue is General Admission, followed by Jeeter and Back Forty. However, Dime Bag sells the most units, followed by Back Forty and General Admission.
The top-selling pre-roll product in Ontario is Jeeter’s Baby Jeeter 2.5-gram Infused Pre-Roll 5-pack.
The British Columbia Pre-Roll Market
Moving west to the second-largest province tracked by Headset we come to British Columbia, where pre-rolls have the highest market share of any province at 37.5%, due, in part, to BC’s long association with pre-rolls
In total, consumers in British Columbia purchased 15.5 million pre-roll products totaling $297.9 million in revenue. However, both of those numbers are slightly down from the year before, though both are by less than a single percentage point, indicating a fully mature pre-roll market.
Pre-rolls in British Columbia have an average item price of $19.29, equalized to $8.49 per gram.
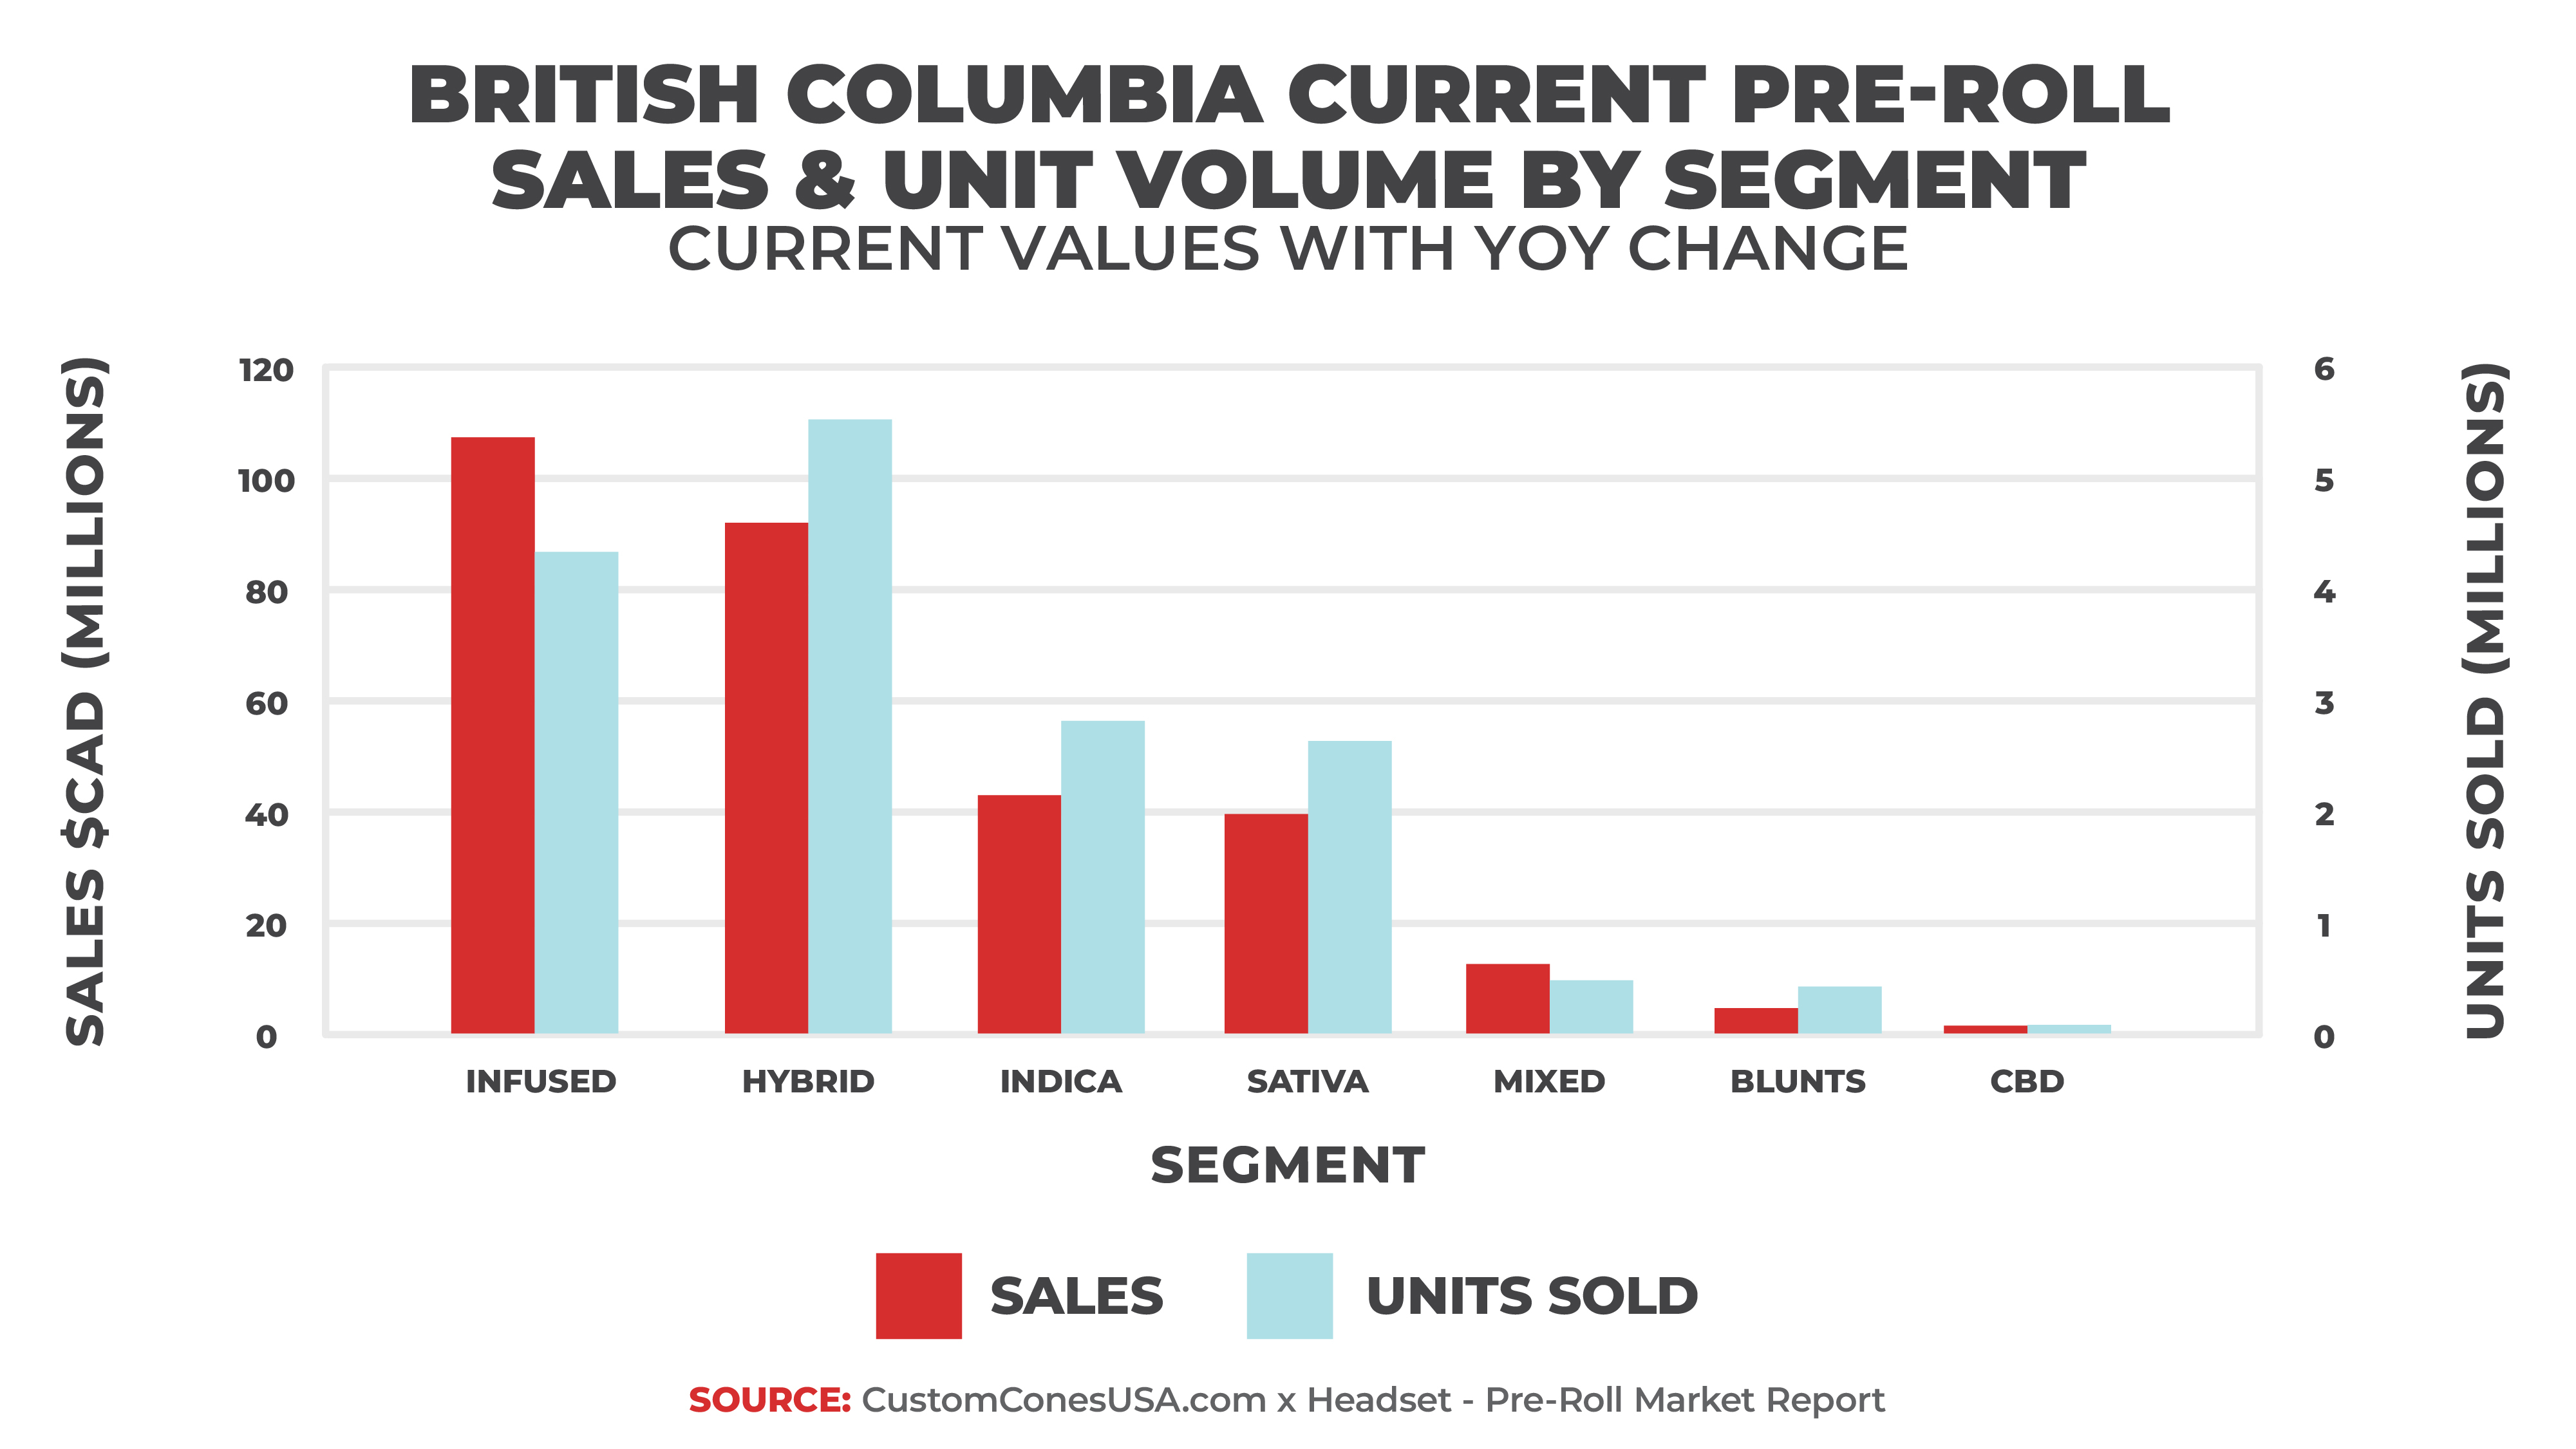
The infused segment takes the top revenue spot in BC, generating $107.4 million on sales of 4.2 million units. However, by unit sales, hybrid pre-rolls claim the top spot with 5.2 million sold, bringing in about $91 million in sales.
Like in other provinces, the indica pre-roll saw the largest gains in revenue, jumping 8.7% year-over-year to pull in $41.8 million on sales of 2.7 million units. However, the largest jump in unit sales came in the mixed strain category, which grew 12%, though the segment is much smaller, selling just 676,000 units.
The top pre-roll brand by revenue in BC is General Admission, followed by Weed Me and Jeeter. However, Station House sells the most units, followed by Thumbs Up Brand and General Admission.
The top-selling pre-roll product in BC, however, is the Claybourne Co.’s 2.5-gram Frosted Flyers Infused Variety 5-pack.
Alberta Pre-Rolls
Alberta residents bought 18.1 million pre-rolls in 2025, generating $354.6 million in revenue. Pre-rolls are the top category in Alberta with a 35.5% market share, the second-highest among all provinces.
Both revenue and unit sales are up from 2024, with revenue jumping 9.9% year-over-year and units sales climbing 5.1%, driven by steep growth in the infused category, which has a higher price point.
The average pre-roll unit price in Alberta is $19.56, with an equalized average price point of $8.46 per gram.
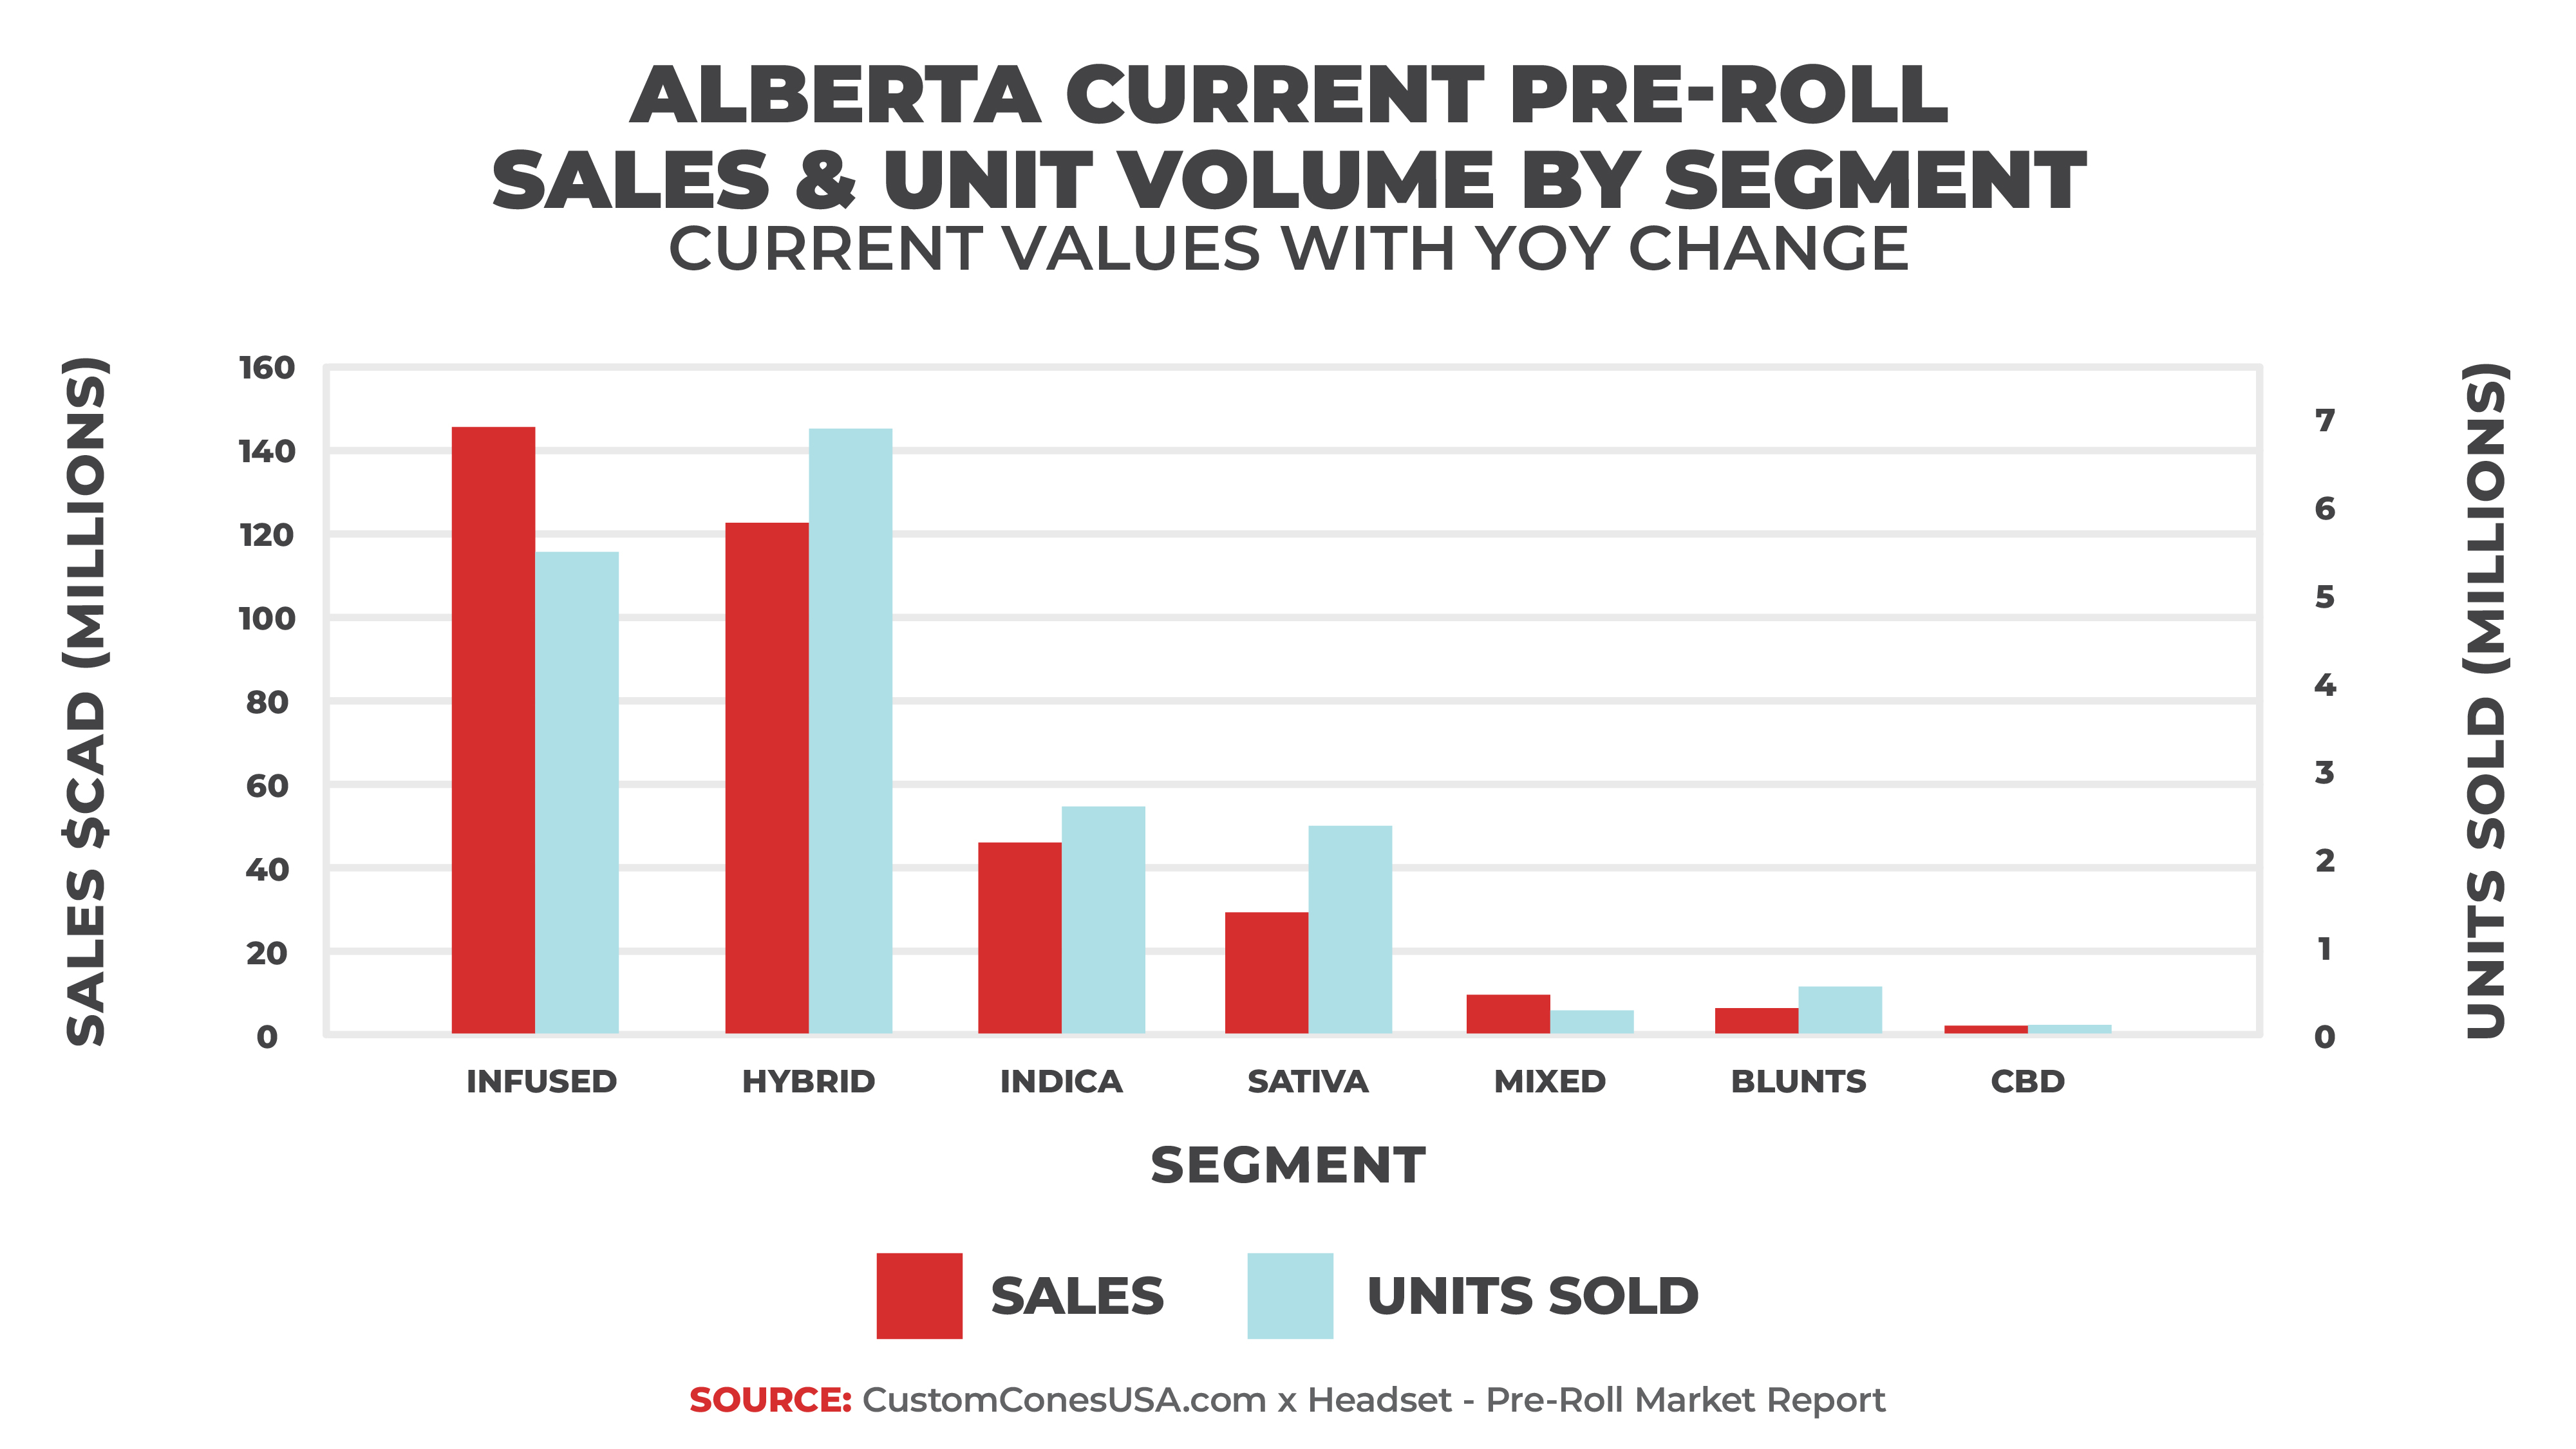
Infused pre-rolls take the top revenue spot in Alberta, generating $143.6 million on sales of 5.5 million units. That’s up 13.1% year-over-year in revenue and 8.4% in unit sales. However, once again, when we turn our attention to unit sales, the hybrid segment moves to the top spot once again, despite a 3% year-over-year drop in unit sales to 6.8 million, generating $121.5 million, which was up 3.2%.
The indica segment, however, again posted the largest growth numbers, with revenues jumping a massive 36.7% to $42.5 million and unit sales climbing 35.7% to 2.6 million.
The top pre-roll brand in Alberta in 2025 by revenue is General Admission at $29.8 million on sales of 925,000 pre-roll units, followed by Space Race Cannabis ($18 million) and Claybourne Co. ($17.2 million). However, the top two places flip when we turn to units sold, where Space Race Cannabis climbs to the top, selling 1.4 million pre-roll units, or 7.6% of all pre-rolls bought in Alberta in 2025. General Admission ranks second by units sold, followed by Spinach with 755,000.
And like in BC, the top-selling pre-roll product in Alberta is the Claybourne Co.’s 2.5-gram Frosted Flyers Infused Variety 5-pack.
The Saskatchewan Pre-Roll Market
The smallest tracked province, Saskatchewan is also, unsurprisingly, the smallest pre-roll market, with pre-rolls having a market share of only 26.5%, third among the categories.
Saskatchewan consumers still bought $56.5 million in pre-rolls in 2025, up 11.8% from 2024. Unit sales were also up 13.4% to 3.3 million units.
Looking at the segments, Saskatchewan shows a heavy preference for hybrid pre-rolls, which generated $25.8 million in revenue on sales of 1.7 million units, easily the top in both metrics. That’s up 11.8% and 12.7% year-over-year, respectively. Coming in a distant second was the infused segment, which saw revenues of $15.1 million, up just 1.1%, on sales of 626,000 units, down 6.9% from 2024.
Indicas follow with about $7 million in sales, moving 455,000 units, which is up 27.1% and 34.7%, respectively. However, sativa pre-rolls saw an even bigger jump in revenue, growing 46.7% to $6.1 million on sales of 401,000 units, up 33% year-over-year.
But the segment that showed the single biggest growth, potentially due to relatively small numbers in 2024, was the blunt category, which saw revenues jump a massive 53.4% in 2025 to $1.3 million, and unit sales jump an even bigger 58.6% to 53,000.
The average price of a pre-roll product in Saskatchewan is $17.06, the lowest of any province, with an equalized price of $7.85 per gram.
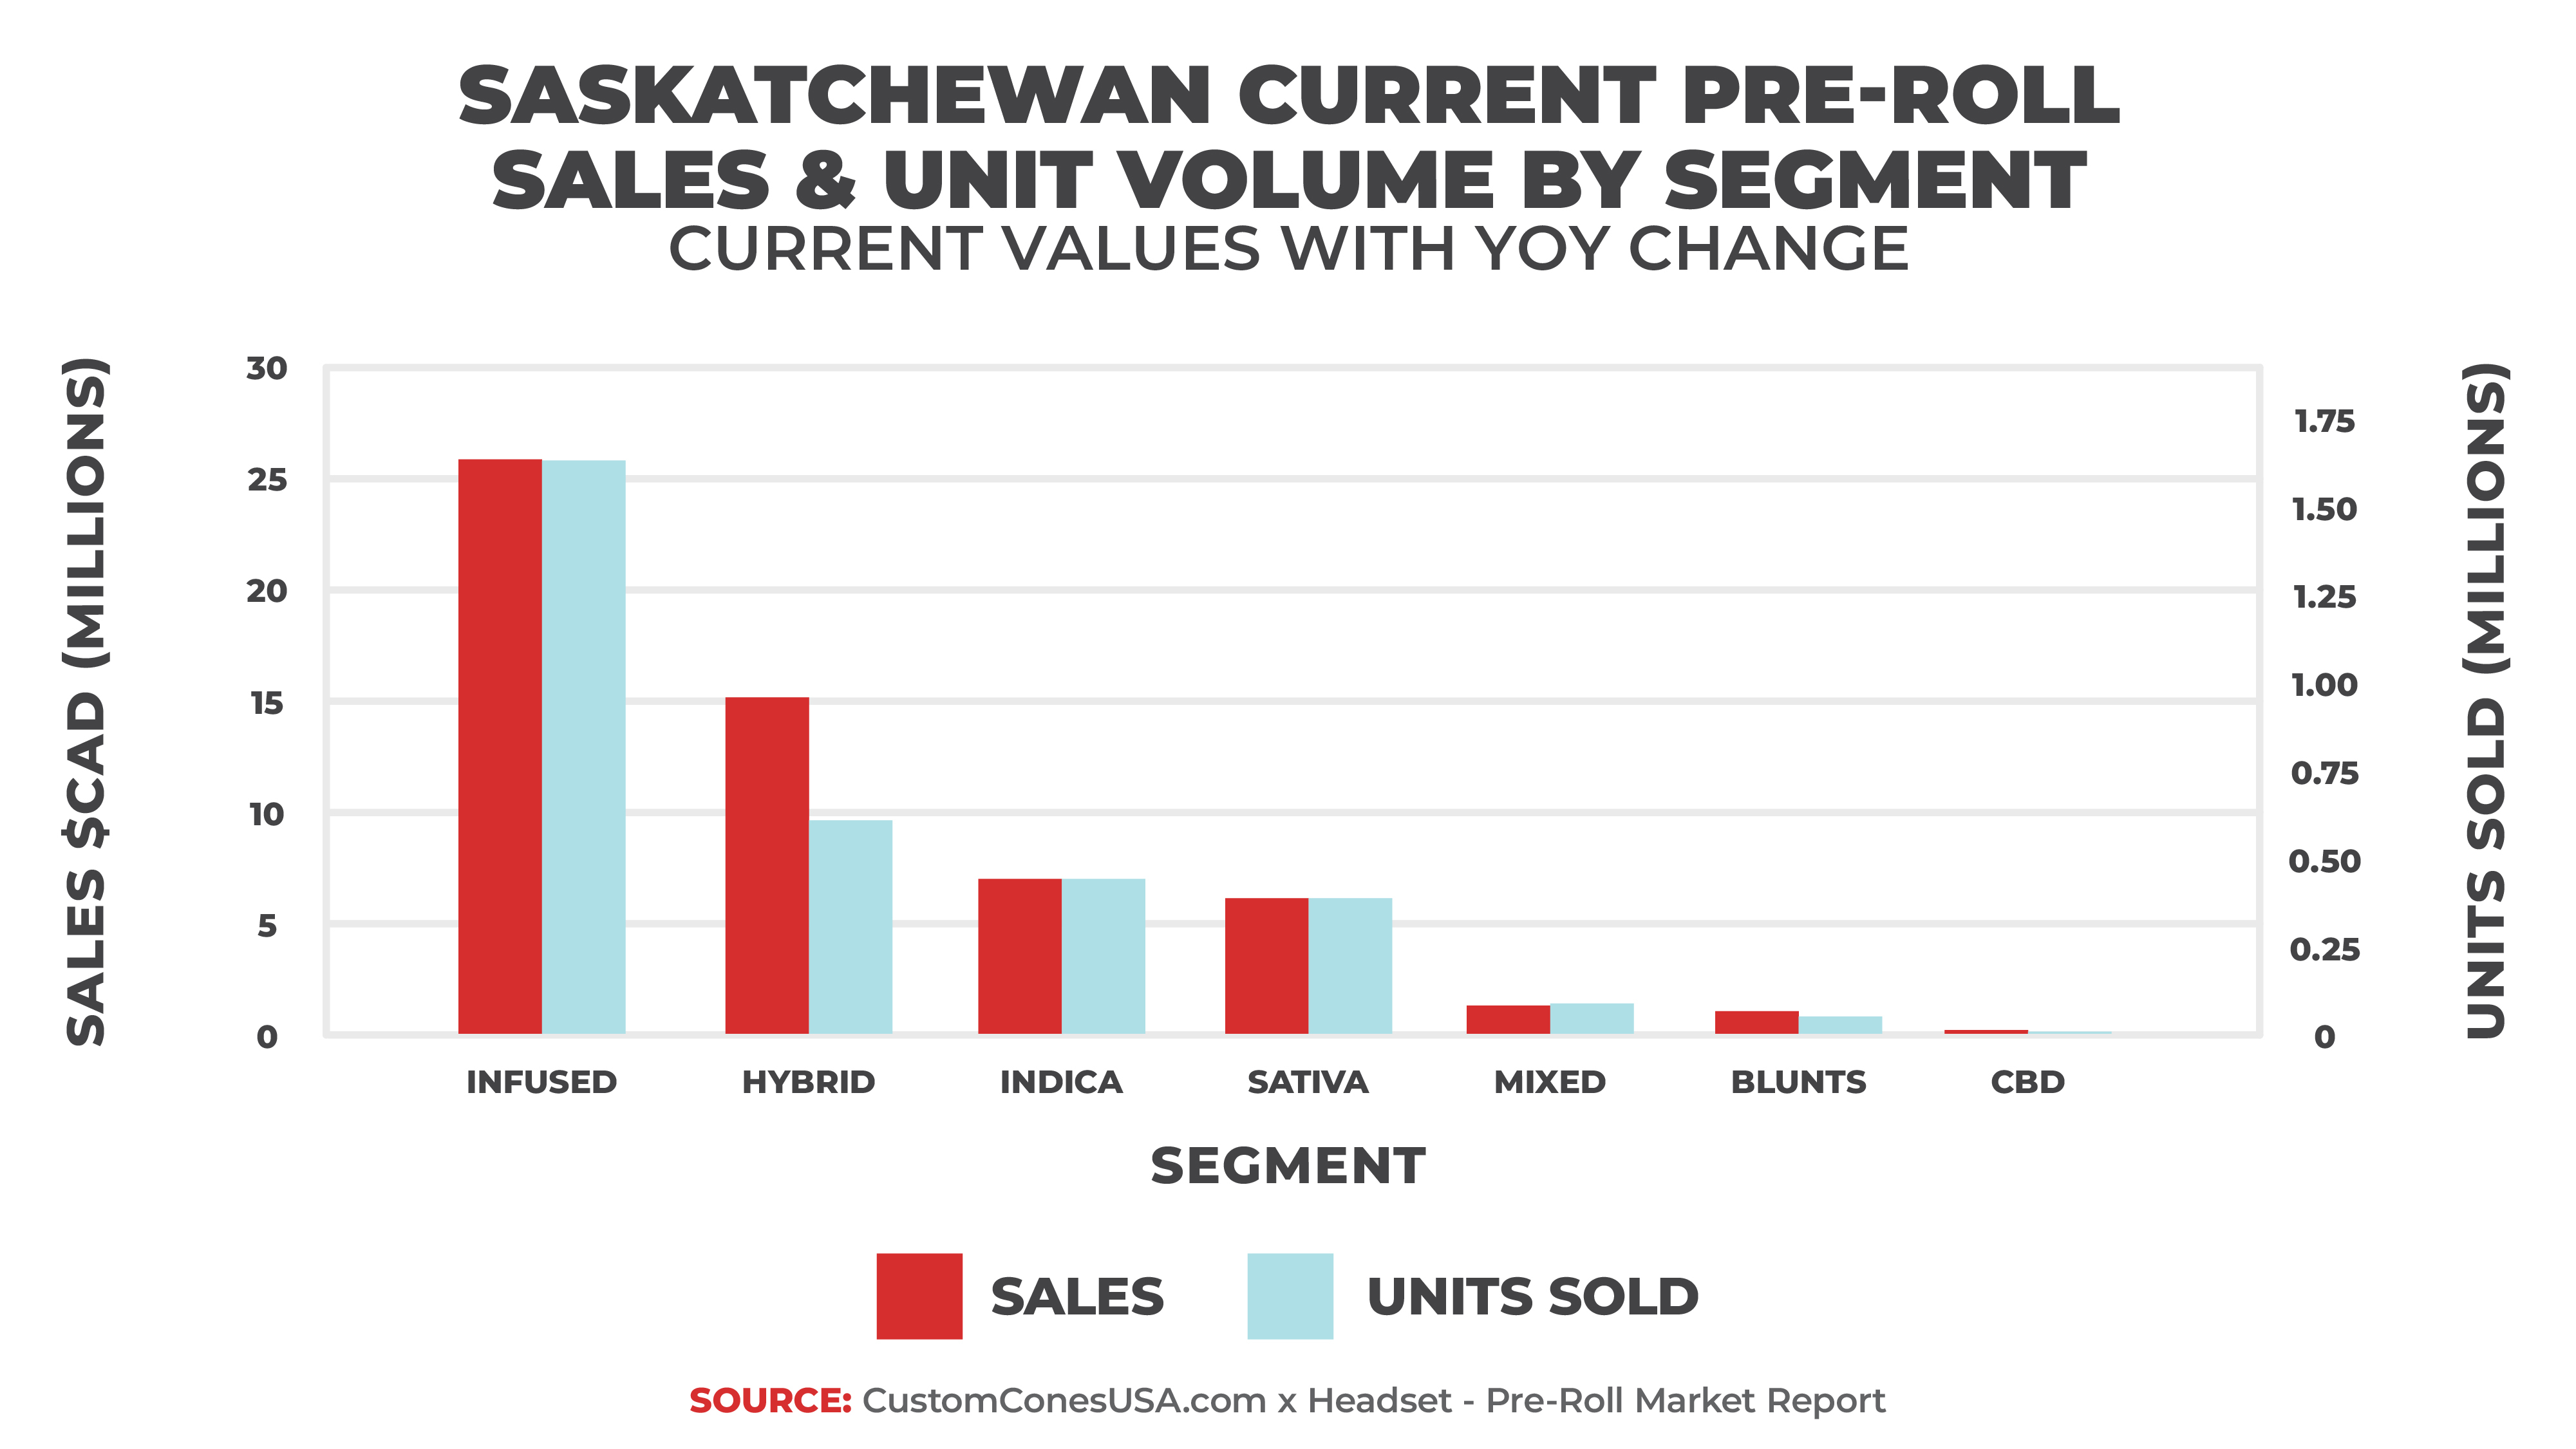
The top pre-roll brand in the province by revenue is Back Forty, which makes four of the top 10 best-selling pre-roll products in the province, generating $4.4 million in revenue on sales of 189,000 units. BOLD takes the second spot in revenue at $3.2 million, followed by Spinach at $3 million.
In unit sales, the top spot belongs to Fuego Cannabis, which sold 260,000 pre-rolls, but only generated $1.7 million in revenue. Back Forty lands in second with 188,000 units sold followed by Space Race Cannabis at 163,000.
The top-selling pre-roll product in Saskatchewan is the Rogue Botanicals 2-gram Cambodian Pre-Roll 4-pack, a sativa product.
Pre-Roll Profit Margin
While there is no direct data on the profit margin for pre-roll producers, we can look at what pre-rolls mean for retailers. And though pre-roll prices have been consistently falling for both retailers and consumers, the margin has remained relatively similar, though it has fallen slightly over the past few years.
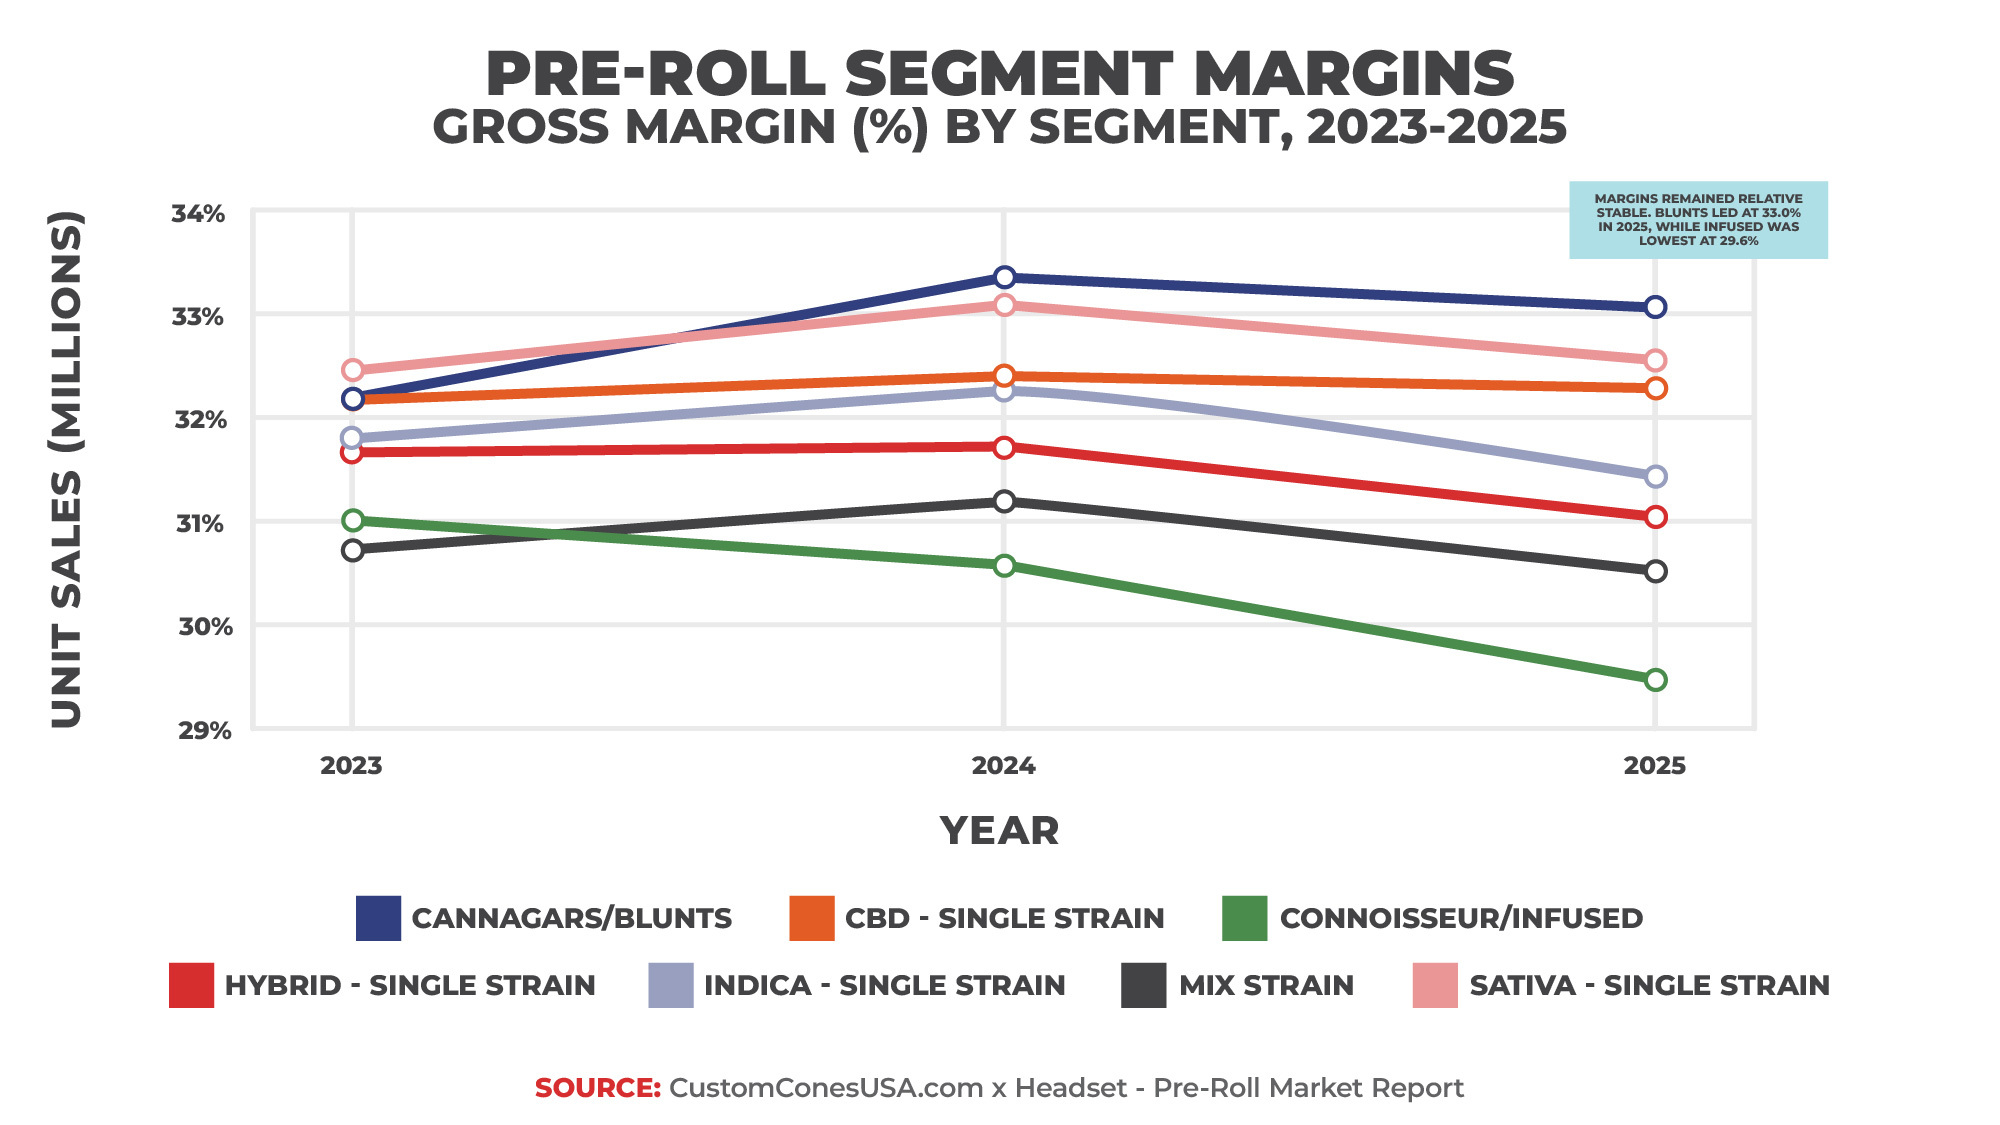
One way to look at the margins for pre-rolls is by looking at total revenue ($1.43 billion) and total cost, which Headset also tracks ($922 million). Using those numbers, we get an overall margin of about 30.8%.
Using the same numbers from 2024 ($1.35 billion in sales and $922 million in cost), we get a margin of about 36%, the same as in 2023.
But once again there is some minor variance within each of the segments. Interestingly enough, the segment with the lowest profit margin for retailers is the infused segment at 29.6%, followed by the mixed strain segment at 30.6%.
The highest margin is in blunts at 33%, followed by sativa at 32.6%.
Pre-Roll Profit Margin by Segment
| Blunts | 33% |
| Sativa | 32.6% |
| CBD | 32.3% |
| Indica | 31.4% |
| Hybrid | 31.1% |
| Mixed Strain | 30.6% |
| Infused | 29.6% |
Canada’s Top Pre-Roll Brands in 2026
In total, there were 649 distinct brands selling pre-rolls across Canada in 2025. That is up from 634 the year before.
However, it is not as simple as 15 new brands coming online; there is also considerable churn underneath.
For example, looking at the data from each year, there are 90 brands that were active in 2024 that did not make it to 2025. Then in 2025, we saw 105 brands make their first appearances.
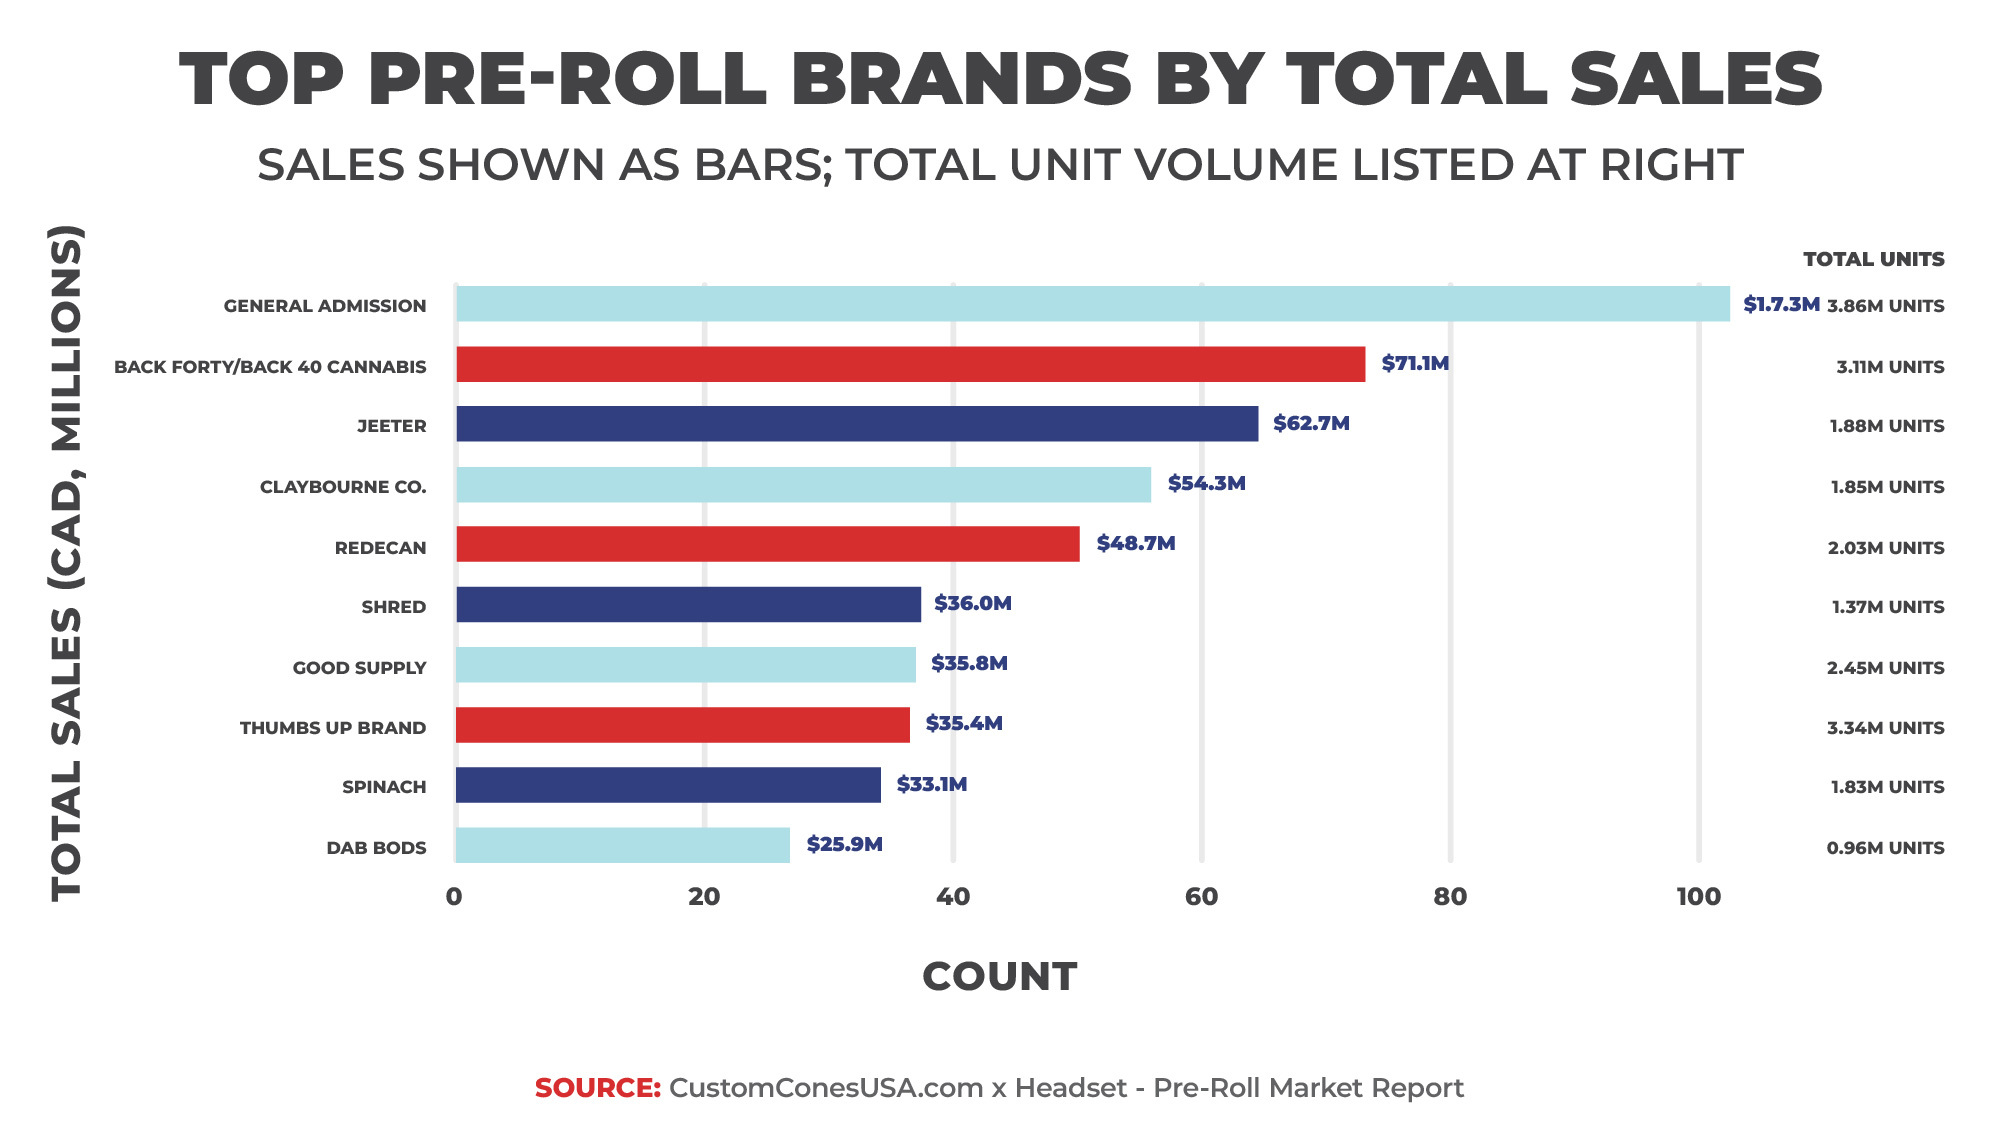
The top pre-roll brand by revenue in Canada is, by far, General Admission, which made $107.3 million in 2025, accounting for 7.5% of all pre- roll revenue in the country. General Admission almost exclusively sells infused pre-rolls, with an average price of $28.12 per unit, about $10 higher than the overall average item price.
Back Forty placed second in revenue with $71 million, followed by Jeeter at $62.7 million.
Turning to units sold, General Admission once again sits in the top spot, moving 3.8 million units or 4.9% of all pre-rolls sold throughout the country. The Thumbs Up Brand, which finishes eighth in revenue, sits in second with 3.3 million units sold, followed by Back Forty at 3.1 million.
It is worth noting though that the no. 4 brand by units sold, Station House, doesn’t even crack the top 20 in revenue, selling 2.6 million units with an average price point of $7.20, the lowest of any brand in the top 30, for revenues of just over $19 million.
The pre-roll brand that made the biggest splash in the Canadian market in 2025 might be Claybourne Co., which is based in California and launched its first Canadian pre-roll products in the fourth quarter of 2024 and immediately began climbing the sales charts.
Claybourne landed four products in the Top 50, including the No. 1 pre-roll product in the country: Frosted Flyers Variety Pack Infused Pre-Roll 2.5-gram 5-pack. Those four products led Claybourne to the no. 4 spot by revenue in 2025, with total sales totaling more than $54.3 million
|
|
Brand Name |
Total Sales |
Total Units |
# of Products |
Average Item Price |
Average EQ Price |
|
1 |
General Admission |
$107,287,651 |
3,815,834 |
59 |
$28.12 |
$15.80 |
|
2 |
Back Forty / Back 40 Cannabis |
$71,086,864 |
3,111,519 |
40 |
$22.85 |
$6.17 |
|
3 |
Jeeter |
$62,709,595 |
1,881,378 |
39 |
$33.33 |
$14.80 |
|
4 |
Claybourne Co. |
$54,321,620 |
1,846,350 |
25 |
$29.42 |
$15.31 |
|
5 |
Redecan |
$48,700,321 |
2,029,983 |
41 |
$23.99 |
$5.13 |
|
6 |
Shred |
$36,022,136 |
1,374,295 |
38 |
$26.21 |
$7.22 |
|
7 |
Good Supply |
$35,766,263 |
2,448,584 |
79 |
$14.61 |
$6.12 |
|
8 |
Thumbs Up Brand |
$35,368,142 |
3,335,051 |
40 |
$10.60 |
$4.92 |
|
9 |
Spinach |
$33,065,618 |
1,827,822 |
49 |
$18.09 |
$9.53 |
|
10 |
Dab Bods |
$25,926,632 |
956,043 |
75 |
$27.12 |
$12.54 |
The Rise of the Pre-Roll Multi-Pack
Over the past several years, the multi-pack has become the favorite format of pre-roll consumers across Canada, and 2025 might be the year they fully took over. All 50 of the top-selling pre-roll products by revenue in 2025 were multi-packs, up from 48 in 2024.
In fact, according to Headset, 75.2% of all pre-roll products sold in Canada in 2024-2025 were multi-packs.
The most dominant format in 2025, by far, is the 1.5-gram 3-pack of 84mm half-gram pre-rolls, accounting for 27.4% of all pre-roll revenue with about $370 million and 25.1% of all unit sales at 18.2 million.
The 3.5-gram format ranks second with about $182 million, followed by the 2.5-gram 5-pack at $162.7 grams. Interestingly enough, though not the top format, the top 2 best-selling products in Canada are 2.5-gram 5-packs of infused 84mm half-gram pre-rolls.
1-gram packages rank next, selling $149.5 million, though the data does not distinguish between singles or 2-packs.
Switching to unit sales, the 1.5-gram 3-pack leads, followed by the 1-gram size with 12.7 million units and the 2-gram size pack with 9.5 million units.
The multi-pack has become a consumer favorite for a handful of reasons, mainly a lower price-per-unit cost and the convenience of fewer trips to the dispensary.
For manufacturers, multi-packs can bring higher revenues with better margins (due in part to lower packaging expenses) and help lead to brand loyalty through larger purchase commitments.
Who is Buying Pre-Rolls in Canada?
While pre-rolls are a product that appeals across every generation and demographic split, one generation easily dominates the pre-roll market.
Millennials buy more pre-rolls than any other generation, accounting for 47% of all pre-roll purchases across 2024-2025, according to Headset. In addition, approximately 60% of pre-roll buyers are male, with men out-spending women in every generational split.
Data from the single month of July 2026 shows a demographic split common to the category, with millennials buying more than twice the pre-rolls of any other generation, accounting for 48.7% of all pre-roll revenue. Generation X comes in second with 23% of purchases, followed by Gen Z at 22.1% and then Baby Boomers at 6.3%
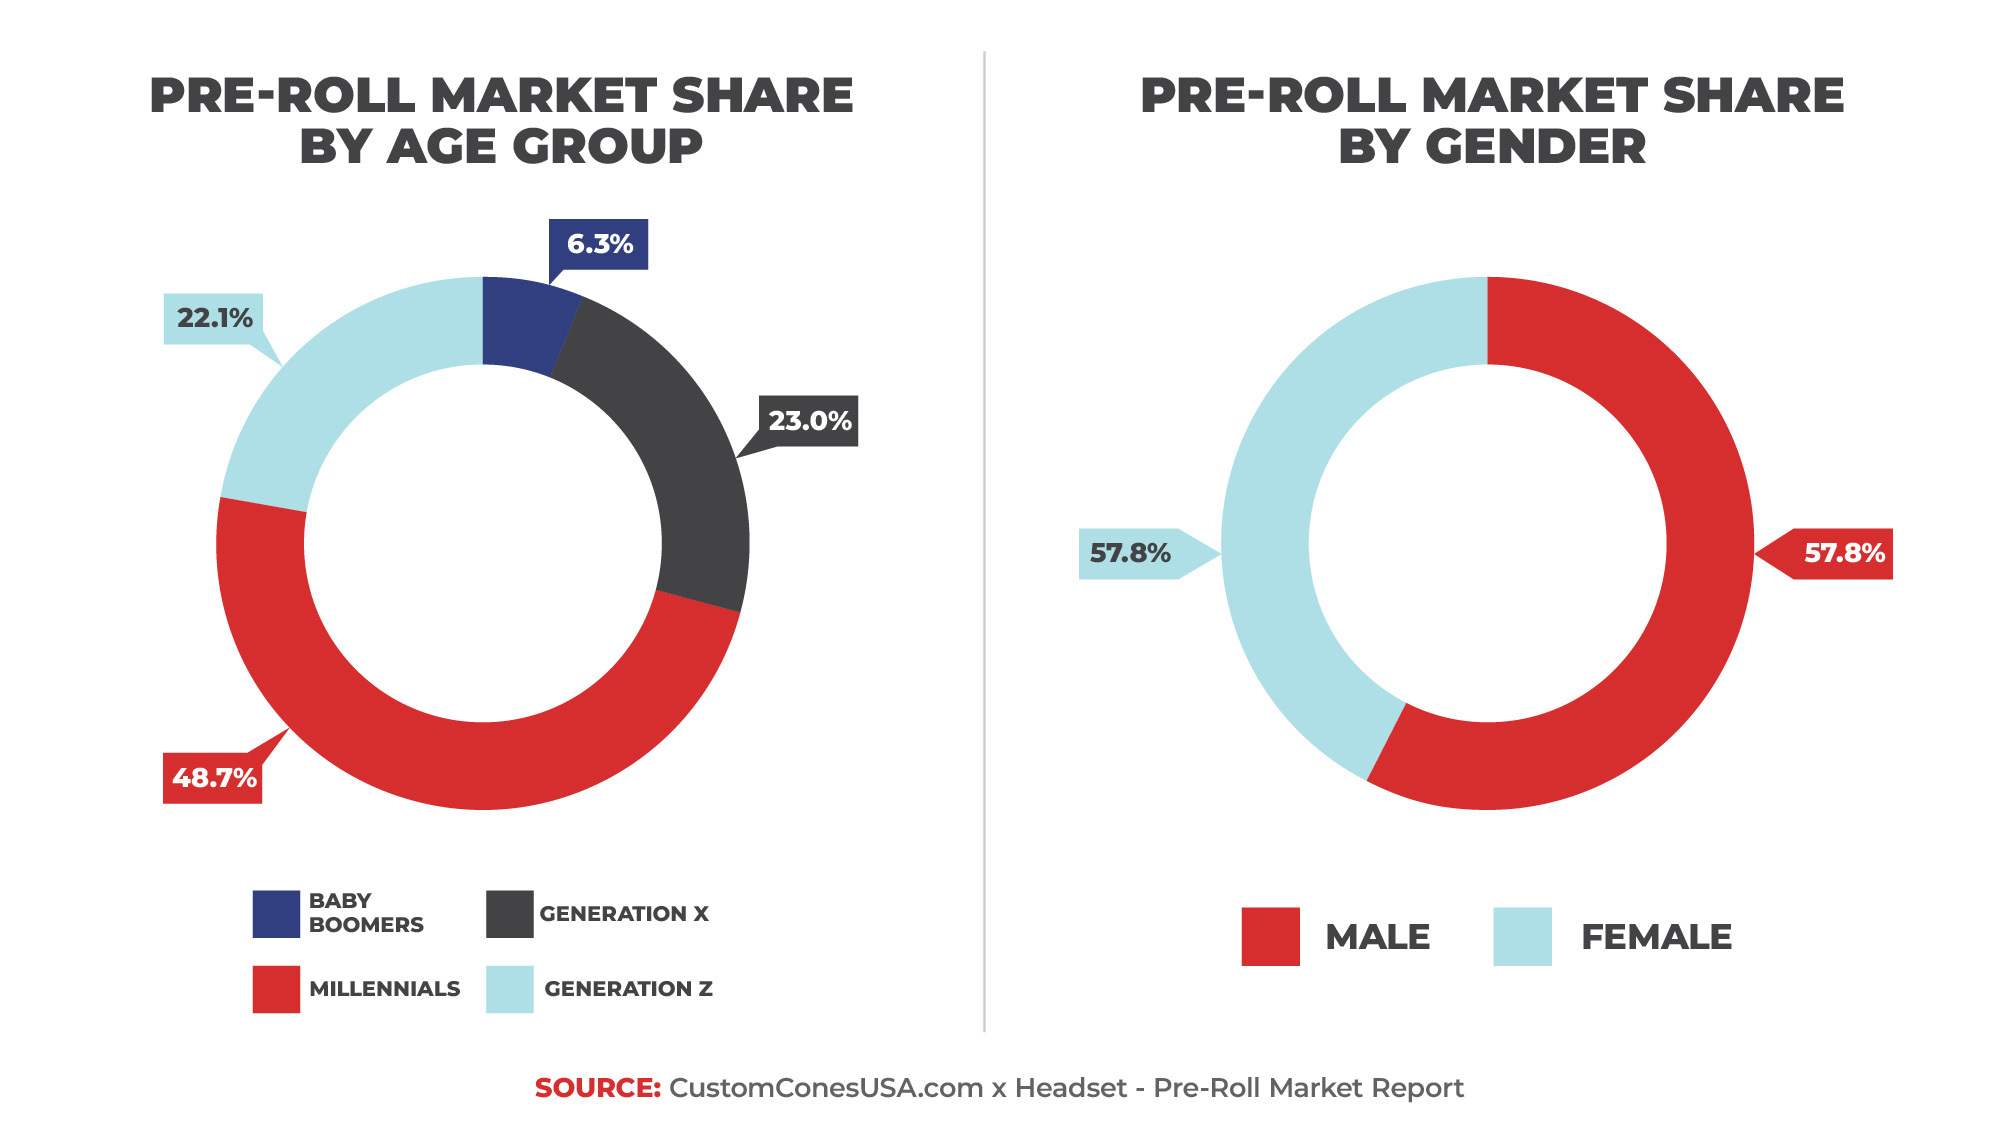
Though Millennials are the key generation brands need to market toward and account for, the largest growth, year-over-year, is in Gen Z. Purchases by Gen Z males are up 4.1%, over last summer, followed by Gen Z females, up 3%. This makes sense considering each year a new cohort of Gen Z reaches the legal age and brands and retailers must take this into consideration when planning marketing and strategy.
Canada’s Top Pre-Roll Products
The pre-roll category is one of, if not the most innovative and experimental corners of the cannabis industry. With low price points and time investments, pre-rolls encourage experimentation from both consumers and LPs, trying new strains, filter tips, infusions and packaging styles.
In fact, of the 5,788 distinct pre-roll products available in Canada in 2025, a full 2,201 were launched in 2025, with 1,748 of those being multi-packs.
Because of that, we see a lot of variance in the top pre-roll products and a lot of turnover in the charts year-to-year including four of the top 10 sellers. For example, a full half of the top 50 products of 2024 dropped off the charts in 2025.
Even the top-selling pre-roll product in Canada in 2025 was a new item: The Claybourne Co.’s Frosted Flyers 2.5-gram Infused 5-Pack. The top product of 2024, General Admission’s Tiger Blood Distillate Infused Pre-Roll 3-Pack (1.5g), fell to the no. 6 spot this past year.
General Admission, while still the top brand in the country by revenue, saw its dominance challenged in 2025. In 2024, the company had 15 of the Top 50 pre-roll products, including the top spot, but in 2025, that fell to nine, which though fewer than the year before was still more than any other LP. Back Forty placed second with seven products (up three from 2024) with Jeeter in third at four.
This year, all 50 of the top-selling products were multi-packs, with 19 of those products featuring infused pre-rolls. Seventeen (17) of the top 50 were hybrid products and another 10 were indica pre-rolls, the segment that saw the biggest gains among the top 50 products.
Here is a look at the top 10 Canadian pre-roll products in 2025:
|
|
Brand Name |
Product Name |
Total Sales Current |
Total Units Current |
Average Item Price |
|
1 |
Claybourne Co. |
Frosted Flyers - Variety Pack Infused Pre-Roll 5-Pack (2.5g) |
$21,451,098 |
602,322 |
$35.64 |
|
2 |
Jeeter |
Baby Jeeter - Multi-Pack Infused Pre-Roll 5-Pack (2.5g) |
$18,689,479 |
500,858 |
$37.16 |
|
3 |
Thumbs Up Brand |
Indica Pre-Roll 2-Pack (2g) |
$13,730,492 |
1,462,746 |
$9.37 |
|
4 |
Thumbs Up Brand |
Sativa Pre-Roll 2-Pack (2g) |
$11,602,848 |
1,210,889 |
$9.54 |
|
5 |
Back Forty / Back 40 Cannabis |
Liquid Imagination Pre-Roll 10-Pack (3.5g) |
$11,427,708 |
554,763 |
$20.49 |
|
6 |
General Admission |
Tiger Blood Distillate Infused Pre-Roll 3-Pack (1.5g) |
$10,938,379 |
456,648 |
$24.14 |
|
7 |
Redecan |
Redees- Hemp'd Animal Runtz Pre-Roll 10-Pack (4g) |
$10,909,530 |
515,091 |
$21.35 |
|
8 |
Back Forty / Back 40 Cannabis |
Lemon Diesel Pre-Roll 10-Pack (3.5g) |
$10,759,440 |
517,262 |
$20.68 |
|
9 |
Jeeter |
Baby Jeeter - Bubba Gum Diamond Infused Pre-Roll 5-Pack (2.5g) |
$10,207,322 |
290,466 |
$35.15 |
|
10 |
Redecan |
Redees - Cold Creek Kush Pre-Roll 10-Pack (4g) |
$10,112,298 |
480,216 |
$21.79 |
Pre-Roll Projections and Trends
While the pre-roll category has grown every year and continues to, that growth is obviously slowing as the Canadian cannabis market continues to matures and begins to plateau. However, we still see the market share for pre-rolls continue to increase as the category continues to drive the entire industry forward, drawing in new customers thanks to continuing innovation and experimentation from LPs.
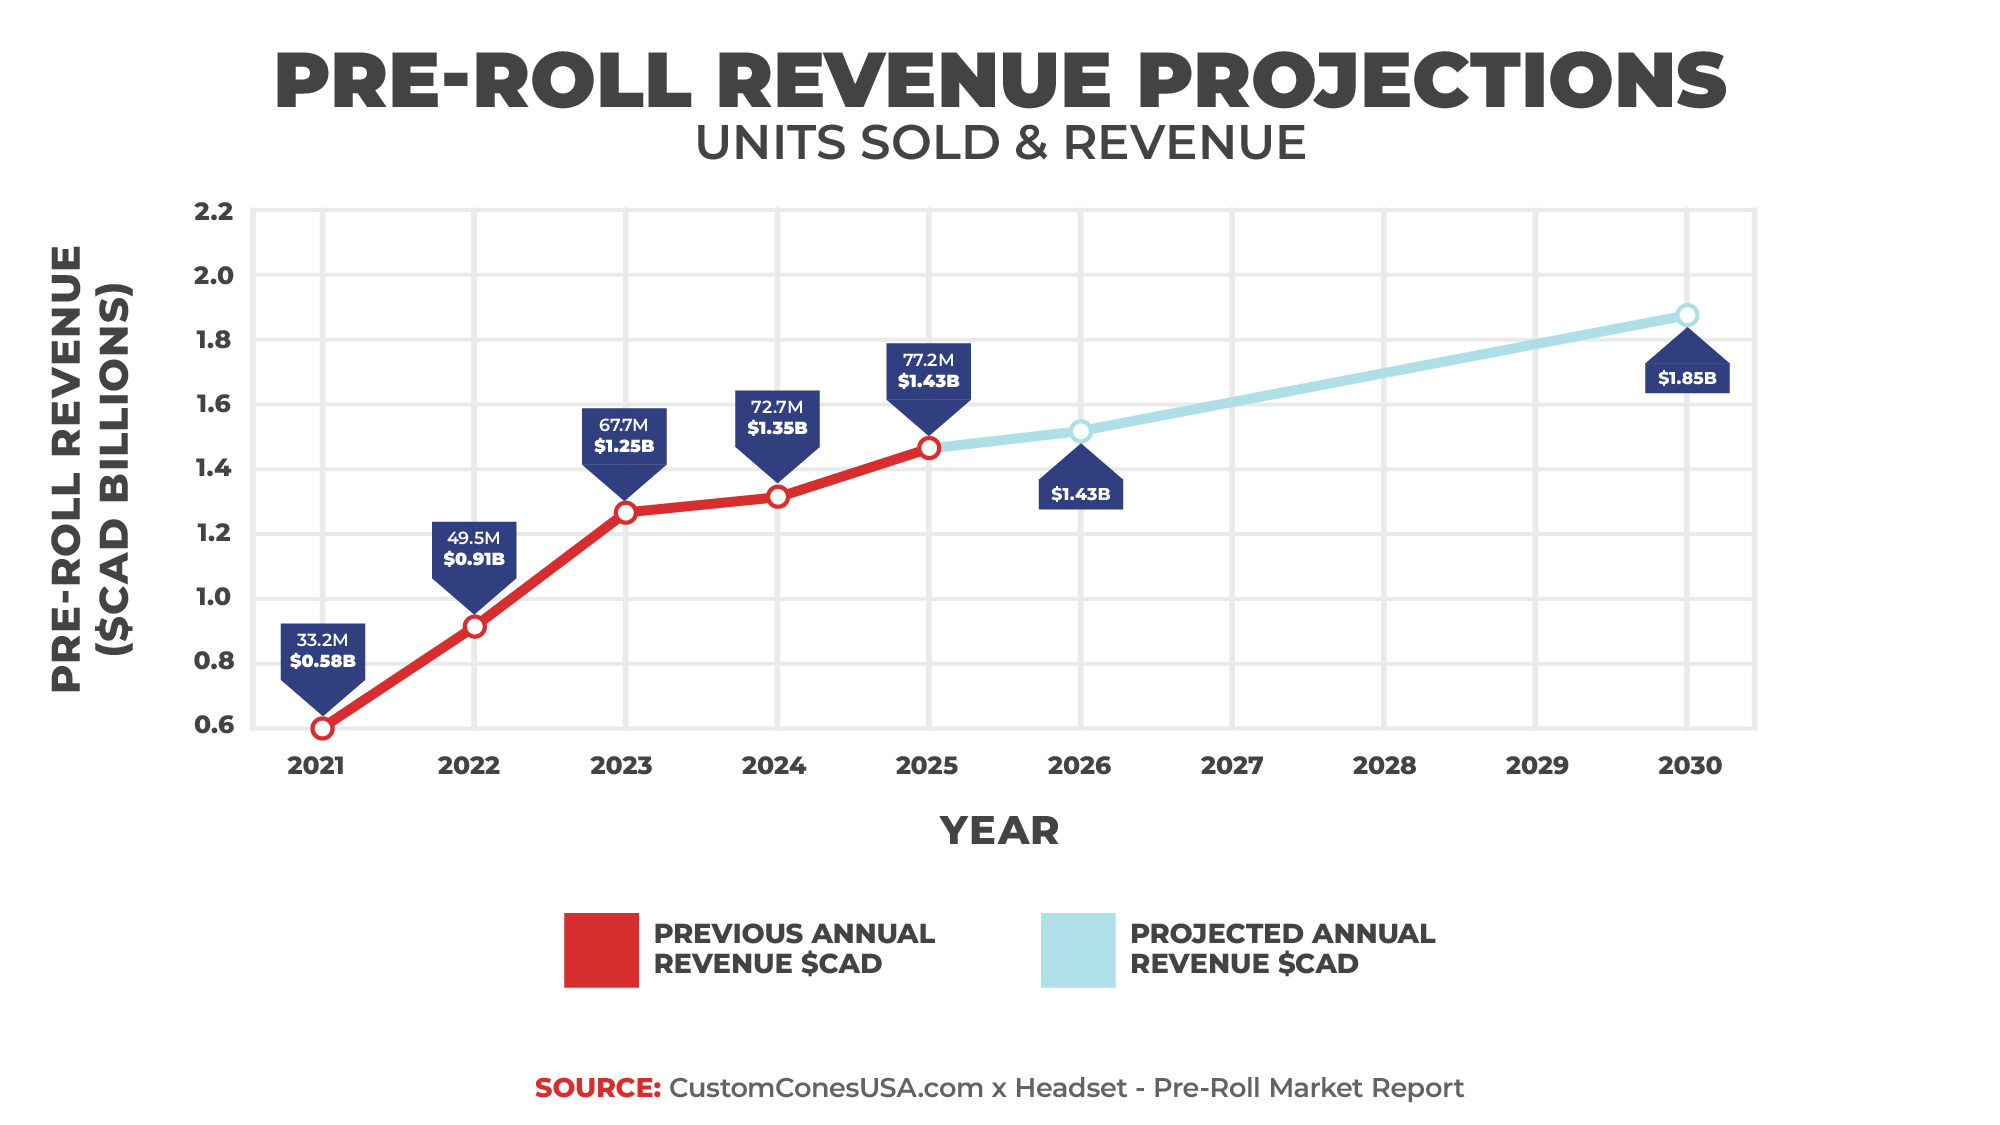
Looking ahead, we took the historical numbers for the category and each of the segments within and applied a compounded annual growth rate (CAGR) that begins around the current rate but assumes that growth will continue to slow to a mature rate of around 2% in 2035. We believe this gives a reasonable, conservative projection of the category's overall growth, moving forward in a mature, fully realized Canadian cannabis industry.
With an overall growth rate of just under 7% for 2026, we are predicting 2026 revenues of about $1.5 billion with unit sales of more than 82.1 million.
Pre-rolls sales will be led by the infused segment, which in 2026 we expect to take the top spot among segments at about $575 million, with hybrids slipping to a close second at $567 million. However, due in part to the differences in price point, hybrids will continue to outsell infused pre-rolls, maintaining control of the no. 1 position in that metric.
We also expect continued growth in the indica segment, which saw the highest year-over-year growth in 2025 after a multi-year decline. The Sativa category also saw growth in 2025 after years of decline as well and may also be starting to turn around.
More than anything, we see this as further indication that pre-roll smokers like to experiment with new strains and new formats, and that the lower price point and smaller unit size of the pre-roll allows for trying new products and brands.
It is also a reason that pre-roll brands must create a wide variety of products, follow trends and keep their offerings fresh throughout the year to remain competitive in the category. The category’s primary competition in the near term is vapor pens, which grew at the same rate in revenue (6.3%) and just slightly more in unit sales (6.2%), and appeals to consumers with the same price, potency and portability concerns.
Pre-roll brands must counter that with premium upgrades that vapor pens cannot add, such as premium filter tips and variety packs, in order to maintain shelf superiority.
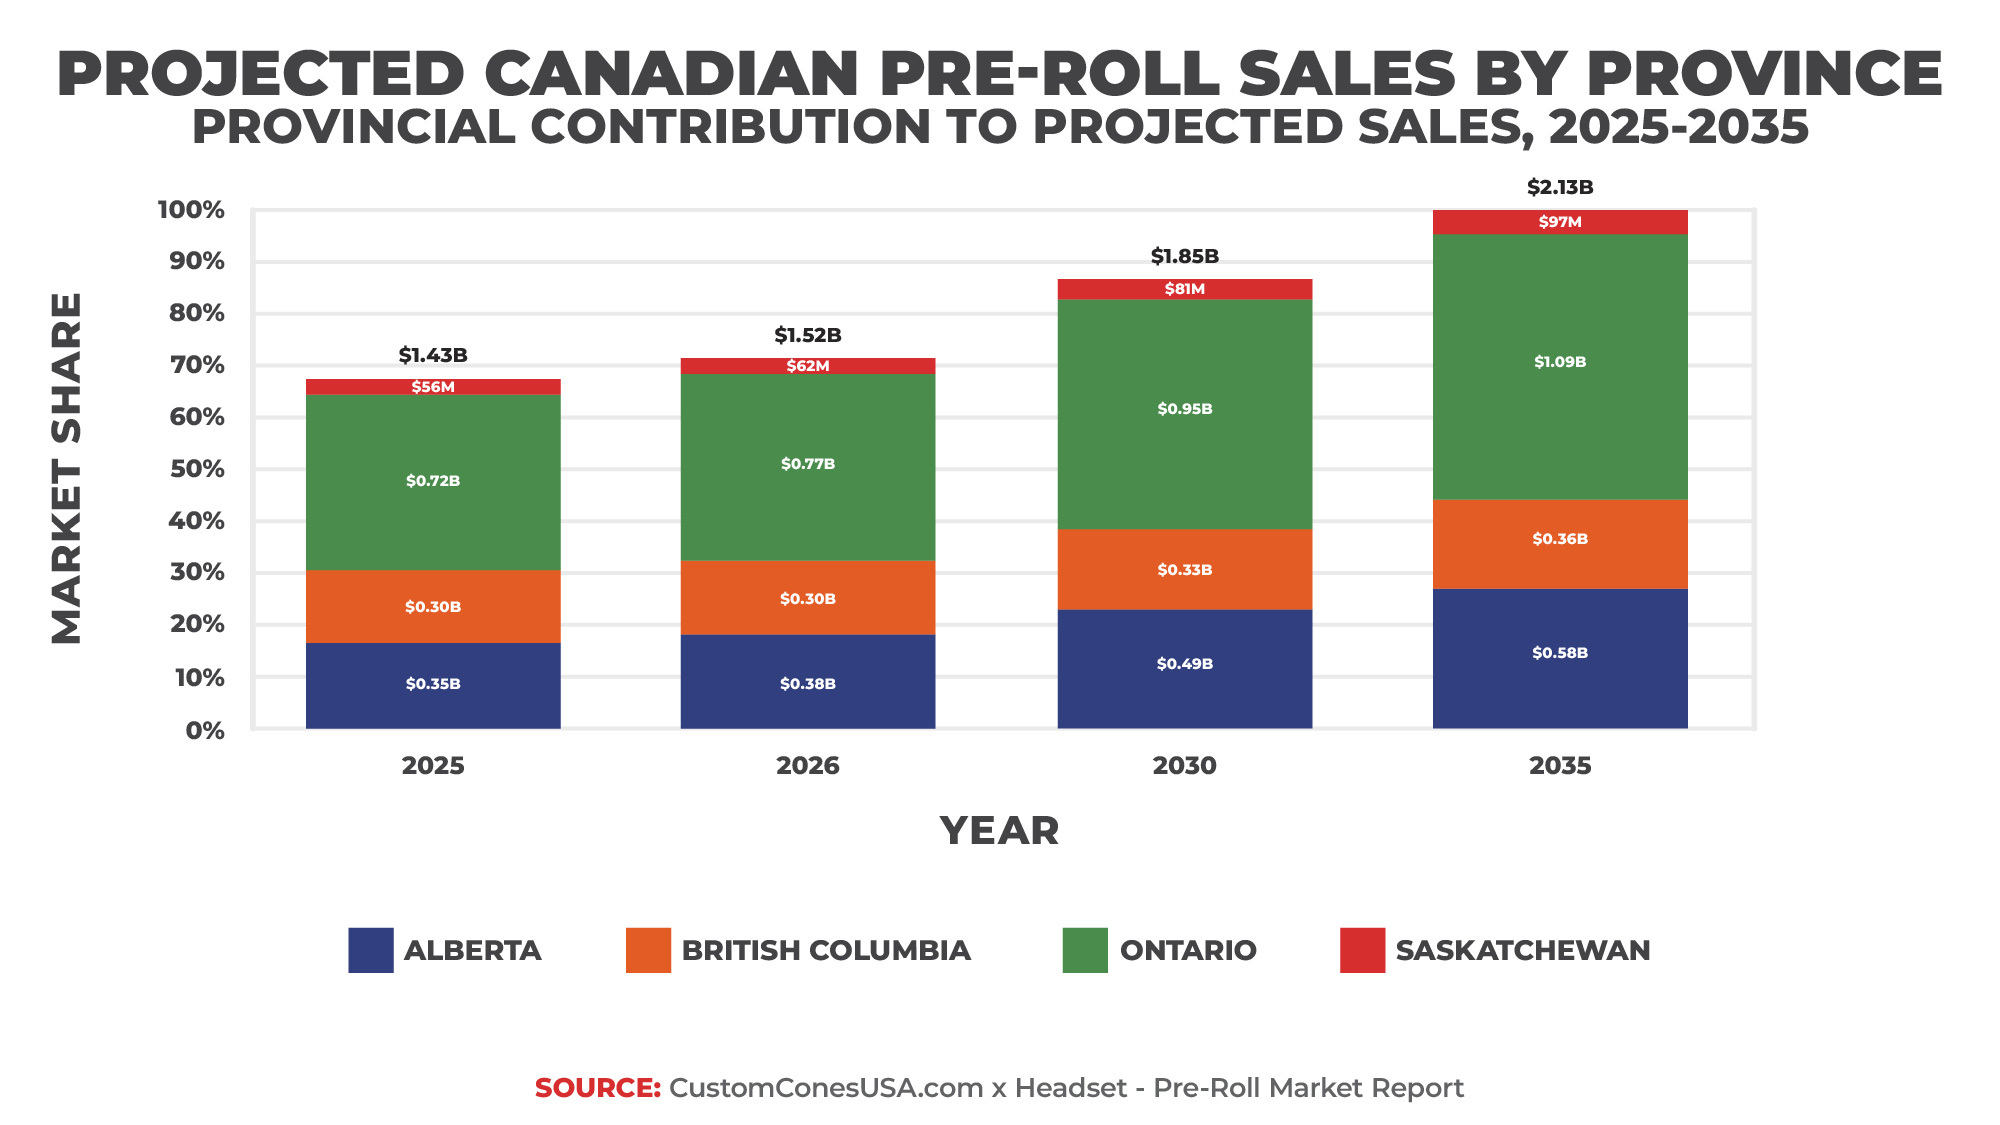
We see Ontario continuing to account for about 50% of the pre-roll market, but Alberta has quietly become a major driver of pre-roll revenues. We also note that Saskatchewan, while small, is the fastest-growing province at 12.6% revenue year-over-year.
We also note that consumers in Saskatchewan lean more toward blunts than any other province. We see the blunt category as a growth segment for the industry as a whole, but particularly in Saskatchewen, which seems to have already made a move toward the segment.
And while we saw some contraction of the British Columbia market in 2025 with most segments showing declines, the indica and mixed strain segments remain strong.
|
Province |
2025 |
2026 |
2030 |
2035 |
|
Alberta |
$354,533,397 |
$383,714,280 |
$491,255,101 |
$577,892,953 |
|
British Columbia |
$297,904,701 |
$303,886,960 |
$328,388,792 |
$362,091,821 |
|
Ontario |
$724,253,971 |
$773,727,692 |
$947,336,499 |
$1,092,757,739 |
|
Saskatchewan |
$56,455,190 |
$61,732,776 |
$81,306,885 |
$96,654,545 |
|
NATIONAL TOTAL |
$1,433,147,258 |
$1,523,061,708 |
$1,848,287,277 |
$2,129,397,058 |
Expanding to a 5-year view, we see continued growth, but a slowing rate as markets mature and begin to plateau. Using individual province data to build projection models, we applied a conservative CAGR of 5.2% and predict the overall pre-roll market will grow to about $1.85 billion by 2030.
Looking out even further, we slowed the CAGR to about 4% for 2035 to account for market saturation as the cannabis industry, and the pre-roll category, reach full maturity, for a projection of $2.1 billion by 2035.
All of those estimates, of course, could change given any regulatory changes by Health Canada or individual provinces.
The State of the Canadian Pre-Roll Market in 2026 and Beyond
No product category in the Canadian cannabis industry sells more units than pre-rolls, and in 2025, pre-rolls passed flower to become the top category by revenue with a market share of 34% and held its position at the top of unit sales, accounting for 39.7% of all cannabis products sold.
That means one of every three cannabis dollars spent in Canada in 2025 went toward pre-rolls.
As LPs continue to innovate and prices continue to fall thanks to competition and new machines that reduce labor issues, such as infusion mixers, closing devices and cone-loading machines, the pre-roll category will only grow in market share in the near future.
The combination of potency and price point – the two most important factors to consumers – found in pre-rolls means the category will not just grow, but drive the industry forward, shaping its future.